Who: U.S. buyers shopping new and nearly‑new cars in July 2026. What: Seven commonly recommended “safe” choices that, in 2026, often add thousands to lifetime cost. When/Where: July 2026, at franchised dealerships and online retail platforms across the United States. Why: Widespread subscription gating, longer loan terms, and shifting resale dynamics have changed the math; what looked conservative in 2024–25 can be expensive today.
Why this matters in July 2026
Through the first half of 2026, industry monitoring shows manufacturers increasingly place functions behind subscriptions, dealers bundle ongoing services into finance deals, and lenders continue to push longer terms to hit target monthly payments. Kelley Blue Book and J.D. Power reporting in June–July 2026 indicate the average transaction price for a new car has settled near $51,000 and the median new‑vehicle loan term is roughly 72 months—figures that amplify the cost of add‑ons and inflated APR assumptions. For buyers investing limited time and money, small, “safe” choices can now compound into large costs.
1) “I’ll put down more cash — that’s always better” (Not always)
Why buyers do this: lower monthly payment, immediate equity. Why it can cost you now: when vehicle models receive rapid mid‑cycle updates or when software‑gated features reduce desirability in the used market, heavy down payments lock capital into an asset that may lose value faster than expected. Also, several captive promotional APRs and loyalty deals in mid‑2026 require low or no cash down to qualify—so overpaying today can make you ineligible for a cheaper financing package.
Practical move: Run the numbers for two horizons: 18 months and the full loan term. Keep 3–6 months of living expenses liquid before committing extra funds to a down payment. If a promotional APR is available only with $0–$500 down, compare total finance cost with and without the cash‑heavy option.
2) “I’ll take the longest loan I can afford — lower payment equals safety” (It amplifies risk)
Long terms—72 months and longer—remain common in 2026. They reduce monthly payments but raise total interest, extend negative equity windows, and increase the chance you’ll owe more than insurance or a trade covers after a loss. According to mid‑2026 loan portfolio summaries from several large banks, the share of new‑vehicle loans at 84+ months has grown year‑over‑year, increasing potential long‑run costs for buyers focused only on monthly payments.
Practical move: Choose the shortest term you can manage without draining emergency savings. Do a worst‑case calculation: "If I total this car at 18 months, what will be my net out‑of‑pocket?" If that number would strain your finances, reduce the loan length or lower the purchase price.
3) “Higher trim = better resale” (The premium often doesn’t stick)
In 2026, buyers see diminished long‑term premiums for tech‑heavy trims. ADAS calibration history, battery health (for EVs/hybrids), and documented maintenance now matter more to used‑car buyers than original trim lines or vanity packages. Dealers and third‑party remarketers price vehicles based on functional health and repair risk, not just sticker equipment.
Practical move: Buy the trim that covers your must‑have features. Avoid paying a large premium for appearance packages or oversized wheels that lower ride comfort and increase tire replacement cost. Spend instead on documented maintenance, factory paint in popular regional colors, and reputable tires that preserve resale condition.
4) “I’ll buy the extended warranty for peace of mind” (Read exclusions closely)
Extended plans still can make sense, but many exclude the very items that carry the highest repair bills today: ADAS sensor replacement and calibration, EV battery module swaps, and major infotainment replacements. Dealer marketing often uses umbrella words like “comprehensive” that don’t reflect exclusions in the fine print.
Practical move (three minutes at the desk): Request the exact contract clause on ADAS, EV battery diagnostics and infotainment coverage. Ask for per‑visit deductibles and maximum payout limits. If coverage is vague or excludes likely high‑cost items, price a repair reserve of $2,000–$6,000 (depending on model) or shop third‑party plans with clear ADAS/EV terms.
5) “Dealer financing is easiest — they’ll give the best rate” (Bring proof)
Dealer financing still offers convenience and occasional genuine promotional APRs, but many mid‑2026 promotions are conditional: you may have to forgo dealer incentives, accept a trade valuation, or purchase add‑on packages. Small APR differences compound over long terms; a 1 percentage point APR gap on a $40,000 loan over 72 months can add more than $2,200 in interest.
Practical move: Obtain a preapproval from your bank or credit union and use it as a negotiating tool. Ask the dealer to beat your preapproval with identical terms and no required add‑ons. If they claim a lower APR, insist that the out‑the‑door math be shown line‑by‑line.
6) “I’ll shop by month: January is best” (Shop the VIN, not the calendar)
Traditional calendar timing matters less when inventory is uneven across models and regions. In July 2026, constrained supply on popular electrified crossovers coexists with plentiful inventory on certain outgoing‑generation sedans. Your negotiating leverage comes from the specific VIN’s days‑on‑lot and incoming stock, not the calendar month.
Practical move: Before visiting, ask the dealer by email or text: “How long has this VIN been on your lot, and is a newer unit incoming?” If the vehicle has been on the lot 30+ days and a replacement is inbound, your leverage increases—regardless of the calendar.
7) “I’ll be nice and simple — I don’t want to haggle” (Precision beats politeness)
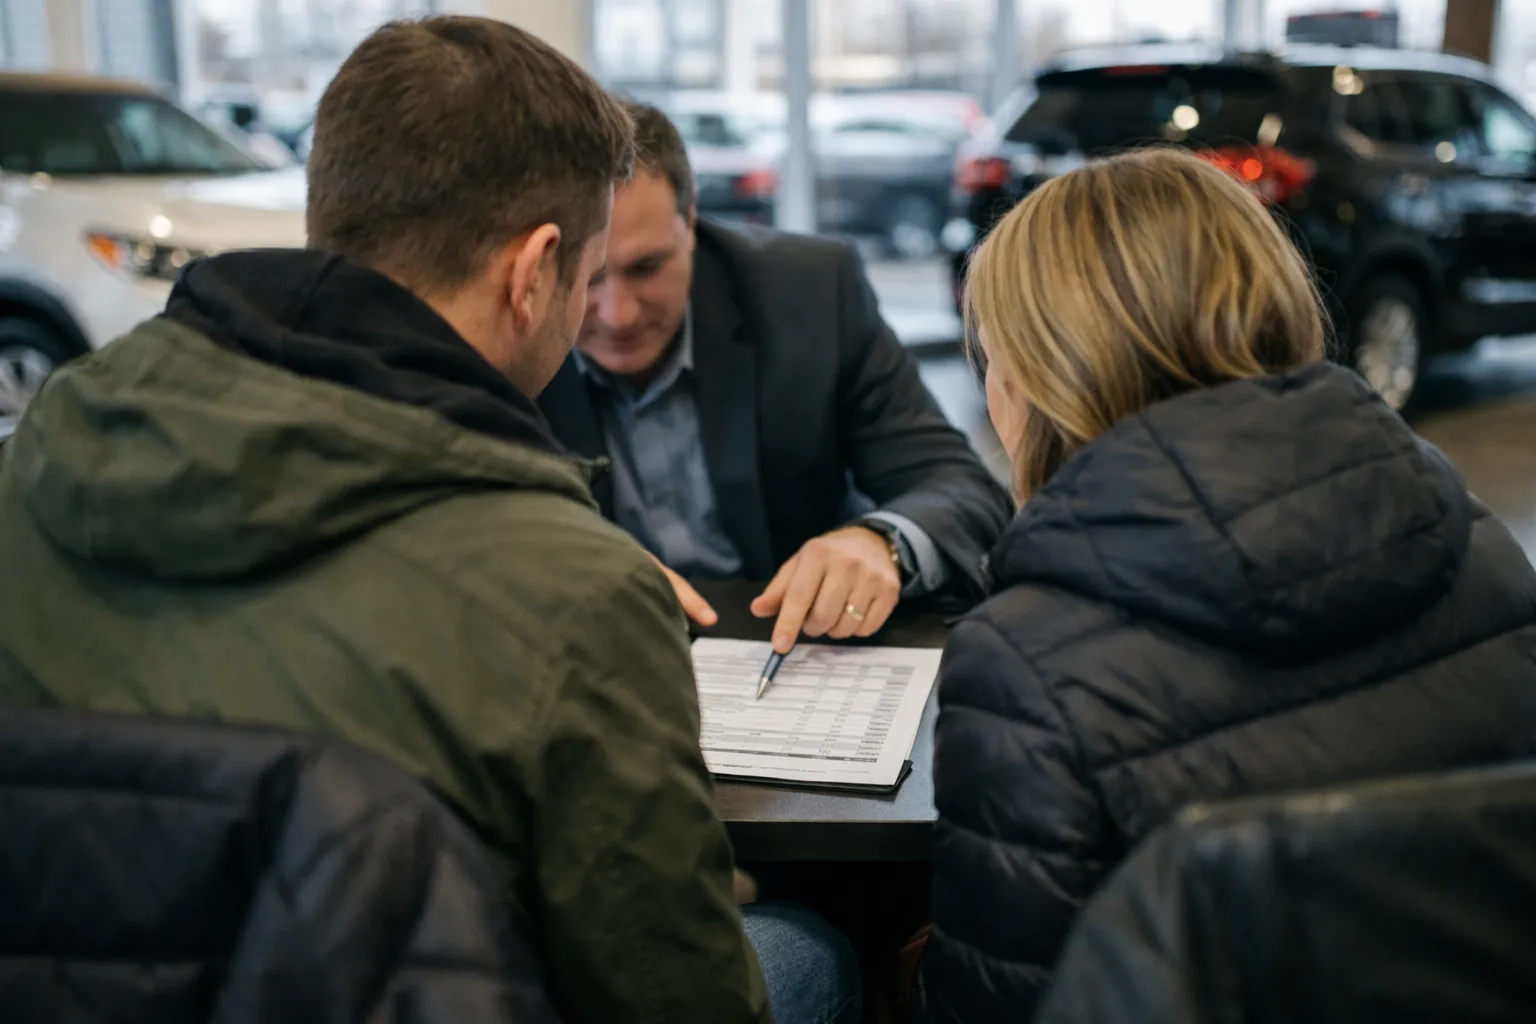
Being easy to work with can cost you. Dealers now use detailed, legally correct language to bundle subscriptions, dealer‑installed accessories, and deferred service charges into contracts. Those items are small monthly or annual drains that add up over ownership.
Practical negotiation script (calm and precise):
- “Send an out‑the‑door price with every fee and add‑on itemized.”
- “Remove these add‑ons: [list]. I’m not paying for them.”
- “If you can do $___ out‑the‑door, I will place a deposit today.”
- “If not, I’ll decide after I check two other stores and return to you with a decision.”
The updated One‑Page Pre‑Test Drive Checklist (July 2026)
- Limit trims to two—avoid option creep that inflates price for little resale benefit.
- Get a written preapproval from a bank or credit union and know your APR and maximum term.
- Quote insurance on the exact VIN/trim and include ADAS and battery replacement exposure.
- Demand an itemized out‑the‑door price by email before you visit—no verbal offers.
- Separate transactions: purchase price, trade value, financing, add‑ons, subscriptions.
- Decide your walk‑away number based both on total cost over 18 months and on the full loan term.
Impact: who this affects and how
These traps hit buyers who skip the arithmetic: first‑time new‑car buyers, EV converts who underestimate subscription and calibration costs, buyers using long loans to hit a monthly budget, and owners of tech‑heavy trims that age poorly in the used market. The financial impact varies—from a few hundred dollars for unnecessary add‑ons to several thousand for long‑term interest, negative equity, or expensive out‑of‑warranty ADAS/EV repairs.
Reactions
Automakers say subscriptions create recurring revenue and allow remote feature updates; manufacturers argue this funds continuous software improvements. Dealer associations note that bundled services streamline sales and aftercare.
Consumer advocacy groups and independent repair advocates have pushed back in 2026, calling for clearer subscription disclosures and easier transferability of subscription entitlements at resale. Several state consumer protection offices have opened inquiries into bundled dealer products and subscription disclosure practices this year; watch for rule‑making or consent orders through late 2026.
What to watch next
Watch for tighter state and federal scrutiny of subscription disclosures and dealer bundling through the second half of 2026. Insurers will publish more ADAS and EV repair‑cost data—expect clearer premium differentials by trim and battery size. Also monitor used‑car remarketing channels for how they value software‑gated features; if resale premiums for feature subscriptions disappear, upfront pricing strategies from 2024–25 will look even worse in hindsight.
FAQ
Should I get a VIN‑specific insurance quote or is a general estimate okay?
Get a VIN‑specific quote. Insurers price on trim, wheel/tire size, safety equipment and—for EVs—battery capacity and replacement exposure. A general estimate can understate premiums by hundreds annually and skew your total‑cost calculation.
Is a dealer‑sold “comprehensive” warranty usually worth it?
Read the contract. If it explicitly covers ADAS sensor replacement/calibration, EV battery diagnostics and infotainment replacement with reasonable deductibles, it can have value. If those items are excluded or the plan caps payouts low, fund a repair reserve instead and compare third‑party plans.
How can I verify a subscription feature transfers to the next owner?
Ask the dealer or manufacturer for the exact transfer policy in writing. Many subscriptions are account‑based, tied to the original buyer’s account, and require an additional transfer fee. If transferability is unclear or costly, treat the feature as short‑term convenience, not long‑term resale value.
One last piece of advice?
Focus on total ownership cost, not just monthly payment. Run numbers for 18 months and for the full loan term, keep liquidity intact, and force every dealer claim into an itemized written line on paper. That’s how “responsible” choices stop being expensive myths.