By David Park, Real Estate & Tax Correspondent
Executive Summary
A Boston‑area couple used Mark’s ongoing pension as a four‑year cash‑flow bridge (2026–2029) to delay both spouses’ Social Security to age 70, while converting $247,000 of pretax retirement savings to a Roth IRA. The updated June 2026 review keeps the original outcomes—a smaller pretax pool subject to future RMDs and a larger tax‑free legacy asset—while adding fresh lessons on Medicare IRMAA timing, state tax sensitivity, and sequencing in a still‑uncertain market.
Background
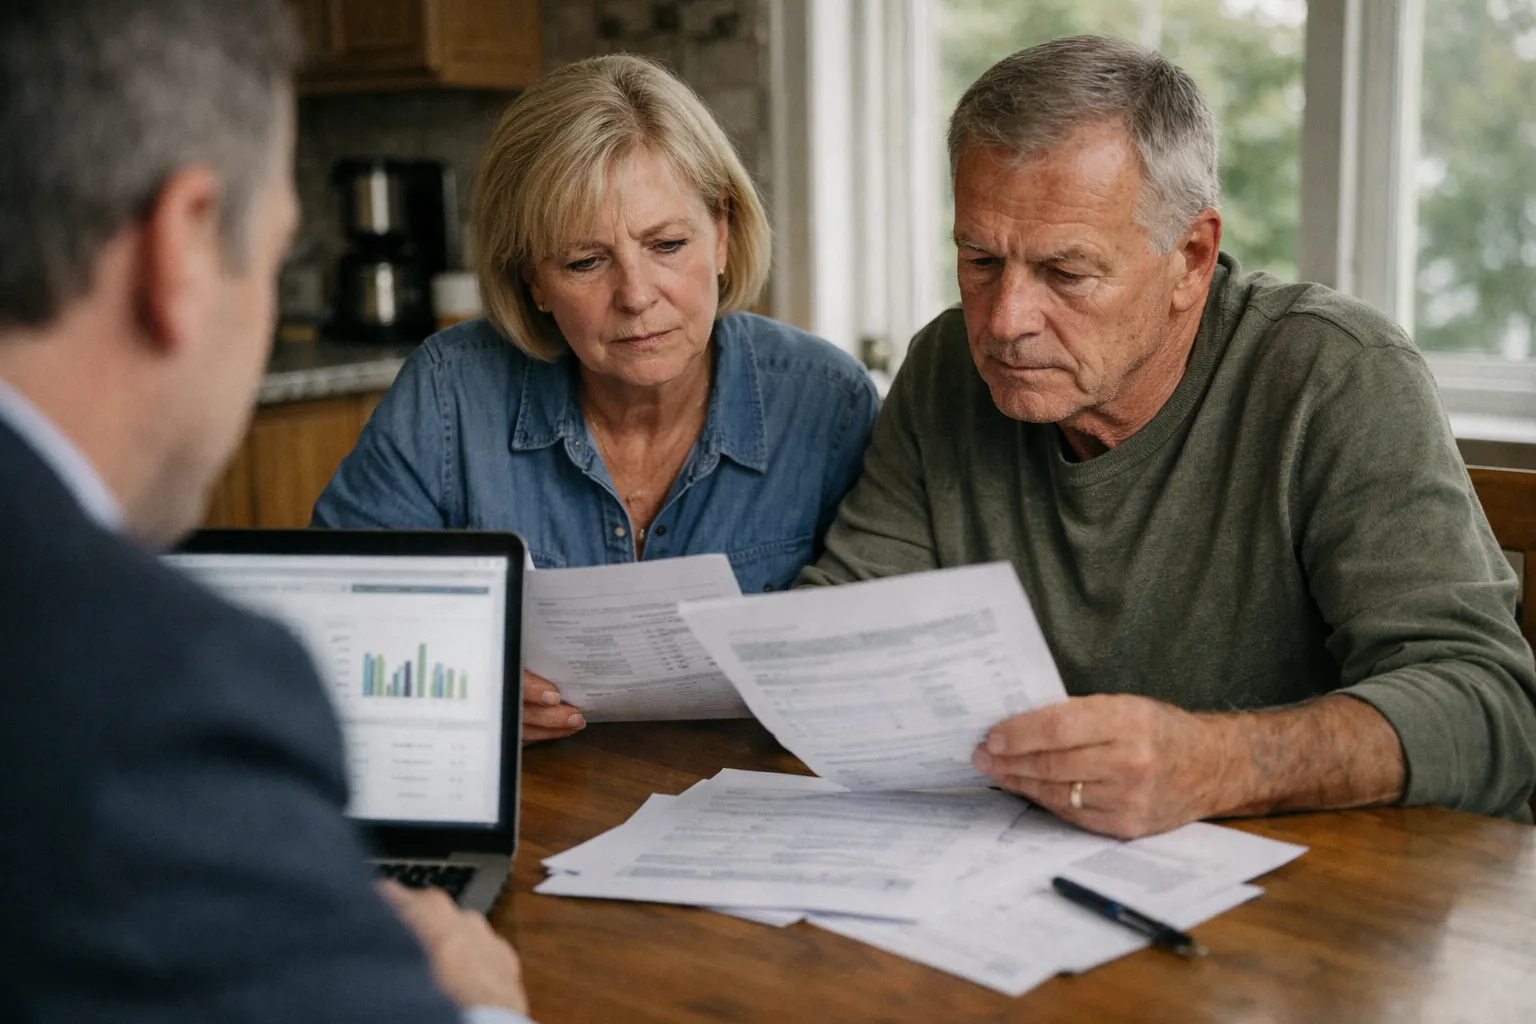
“Mark” (66 in 2026) and “Elena” (64) live in a paid‑off suburban home near Boston (estimated value ~$820,000). Mark began a defined pension in late 2025 of $2,900/month ($34,800/year, no COLA). Elena planned part‑time work through mid‑2027.
- Portfolio (start of 2026): Mark’s rollover IRA: $1.05M; Elena’s 401(k): $410K; joint taxable brokerage: $290K; combined Roth IRA: $185K; cash: $55K.
- After‑tax spending target: $105,000/year, with travel spikes in the first decade of retirement.
- Primary objective: Delay Social Security to age 70 for higher guaranteed lifetime income, shrink pretax IRA exposure to RMDs, and grow a Roth legacy for two adult children.
Challenge
The household faced three tightly linked problems:
- A large pretax balance ($~1.46M combined) that will produce RMDs under current rules.
- The desire to maximize delayed Social Security to 70—trading earlier benefit receipts for up to roughly 8% additional benefit per year delayed (up to ~32% if full FRA is 66).
- Estate goals to limit heirs’ exposure to inherited pretax IRA taxation under post‑SECURE rules.
By June 2026, planners were also flagging two operational threats that change the execution details: (1) Medicare IRMAA continues to use a two‑year lookback of MAGI (so large 2026 conversions can affect 2028 Medicare premiums), and (2) state income tax treatment of retirement distributions can materially change the net benefit of conversions for residents of states like Massachusetts that tax many retirement incomes.
Solution
The planner combined a “pension bridge” with staged Roth conversions sized to fill marginal tax brackets and explicit IRMAA management. Key elements (unchanged in principle from the original plan, but refined for mid‑2026):
- Use the pension as a low‑volatility income floor so both spouses could delay Social Security to age 70.
- Execute partial Roth conversions across 2026–2029 sized to utilize targeted federal brackets while avoiding unnecessary IRMAA exposure and mindful of state tax costs.
- Pay conversion taxes from the taxable brokerage account to preserve converted capital inside the Roth for tax‑free growth and legacy use.
- Preserve the Roth IRA as a late‑life flexibility and inheritance vehicle; leave the Roth untouched during the bridge years.
- Model multiple scenarios—including Medicare IRMAA outcomes, state tax variations, and low‑return sequences—to identify “collision years” when pension + Social Security + RMDs could push them into higher effective tax rates.
Why this still matters in mid‑2026: Roth conversions remain a primary tool to reshape the tax profile of retirement assets. SECURE 2.0’s later RMD ages give some households a longer conversion runway, but IRMAA’s two‑year MAGI lookback and state tax rules can create countervailing risks. The updated plan explicitly models those interactions rather than optimizing only federal bracket fill.
Implementation
Step 1: Four‑year bridge budget (2026–2029)
The couple mapped expected after‑tax needs of $105,000/year and noted higher travel years. Mark’s pension ($34,800) covered many fixed costs, shrinking immediate withdrawal pressure on retirement accounts and enabling deliberate conversion windows.
Step 2: Claiming and timing
They committed to delay Social Security to 70. That choice concentrated taxable events (IRA withdrawals and conversions) into the pre‑Social‑Security years so they wouldn’t overlap with larger guaranteed benefits and later RMDs.
Step 3: Fill‑the‑bracket conversions with IRMAA and state checks
The practical mechanics (actual amounts implemented):
- 2026: IRA distributions $38,000 for living expenses + Roth conversion $52,000 (taxes paid from brokerage).
- 2027: IRA distributions $44,000; Roth conversion $60,000.
- 2028: IRA distributions $55,000; Roth conversion $65,000.
- 2029: IRA distributions $58,000; Roth conversion $70,000.
Total converted from pretax to Roth across four years: $247,000. Converting in these amounts kept their federal taxable income inside targeted bands while limiting IRMAA exposure by avoiding sharp spikes in a single year. Taxes for the conversions were paid from the taxable brokerage account to preserve converted principal.
Step 4: Preserve Roth and coordinate estate mechanics
The Roth was deliberately kept intact as an emergency cushion and a clean legacy bucket. Beneficiary designations were reviewed and updated in June 2026; the couple confirmed that direct beneficiary designations on the Roth align with their revocable trust and estate plan to minimize probate and ease transfer for heirs.
Step 5: Stress testing and scenario planning
Projections included:
- Monte Carlo and deterministic scenarios with 0%–5% nominal return paths to test bracket and IRMAA sensitivity.
- IRMAA simulations using the Medicare two‑year MAGI lookback so 2026 conversions’ impact on 2028 premiums could be quantified.
- State tax scenarios—because Massachusetts taxes many retirement incomes, conversions produced different net outcomes than they would for retirees in tax‑friendly states; planners ran both Massachusetts and hypothetical no‑state‑tax cases to show the difference.
Results
By the end of the four‑year window (2029 projection), the plan produced measurable, modelable outcomes:
- Roth principal increased by $247,000 (plus whatever market returns occurred inside that account), shifting future growth out of pretax IRAs.
- Pretax balance subject to RMDs fell from $1.46M to roughly $1.213M (pre‑growth). In the example projection this reduced annual forced taxable withdrawals at RMD‑age by an illustrative ~$9,900 (comparing a simple 4% withdrawal proxy), lowering future tax pressure in later life.
- IRMAA impact contained: By spreading conversions over four years and limiting single‑year spikes, the couple avoided a disproportionate increase in projected Medicare Part B/D premiums tied to any single year’s MAGI in the lookback window.
- Estate clarity: The larger Roth provides heirs tax‑free flexibility; under common post‑SECURE beneficiary withdrawal rules heirs still face timing constraints, but tax liability is materially lower on Roth distributions.
The bottom line: conversions reduced future forced taxable distributions, preserved higher guaranteed Social Security later in life, and strengthened the tax‑free legacy bucket—outcomes that matter most over multiple decades, not just a single tax year.
Lessons Learned (June 2026)
- Pensions buy sequencing time. A modest defined benefit allows deliberate Roth conversion windows instead of reactive distributions to meet cash needs.
- Model IRMAA and the two‑year MAGI lookback. Conversions paid in years that feed Medicare’s lookback can raise Part B/D premiums two years later; stagger conversions if IRMAA sensitivity is material.
- State taxes change the calculus. Residents of states that tax retirement income (including many Massachusetts filers) should model state rules; net benefit from conversions varies materially by state residency.
- Pay conversion tax from non‑retirement assets when possible. This preserves more tax‑free principal in the Roth while keeping retirement accounts intact for ongoing cash‑flow management.
- Run collision‑year stress tests. Model years when pension + Social Security + RMDs align and test downside returns—these are the years where sequencing mistakes are costly.
Takeaways
- Use predictable pension income to create conversion windows—don’t let cash‑flow pressure force early Social Security claiming.
- Fill federal brackets across pre‑Social‑Security years, but check IRMAA and state tax effects before committing to large single‑year conversions.
- Pay conversion taxes from taxable accounts when feasible to maximize tax‑free compounding inside the Roth.
- Coordinate beneficiary designations and estate documents so Roth assets pass cleanly to heirs.
- Think decades, not quarters: the value of these steps is the multidecade reduction in forced taxable distributions and greater after‑tax flexibility for heirs.
FAQ
How does Medicare IRMAA’s lookback affect Roth conversion timing?
Medicare uses a two‑year MAGI lookback to set IRMAA surcharges for Part B and Part D. That means a large conversion in 2026 can influence Medicare premiums in 2028. Sequence conversions to avoid a single large spike during a year that feeds an IRMAA determination if higher premiums would negate the tax benefits.
Should I pay Roth conversion taxes from the IRA being converted or from brokerage cash?
Paying taxes from taxable brokerage or cash preserves the converted principal to compound tax‑free inside the Roth. It also avoids an additional taxable distribution from the IRA. The tradeoff is depleting liquid holdings, so confirm cash reserves and emergency buffers before using brokerage proceeds for tax payments.
Does my state’s tax treatment change whether conversions make sense?
Yes. Some states tax most retirement distributions; others exempt them fully or partially. For someone in a state that taxes retirement income, the net benefit of converting (federal tax now vs. state + federal tax later) can be reduced. Model both federal and state outcomes before a multi‑year conversion plan.
Can I use other bridges if I don’t have a pension?
Yes. Alternatives include part‑time employment, a bond ladder, short‑term taxable withdrawal plans, or a temporary annuity (including QLACs for a portion of RMD deferral). The goal is predictable low‑volatility cash flow so you can time conversions and Social Security claiming deliberately.
How should I involve heirs and estate counsel?
Coordinate beneficiary forms, trust language, and tax projections with estate counsel so Roths pass efficiently and align with your broader estate plan. Roths can simplify heirs’ tax decisions, but post‑SECURE distribution rules still constrain timing—professional coordination matters.
Disclaimer: This updated case study is educational and reflects David Park’s professional analysis as of June 2026. It is not individualized tax or legal advice. Rules on taxes, Medicare, and Social Security can change—consult a qualified tax advisor or fiduciary planner for advice specific to your circumstances.