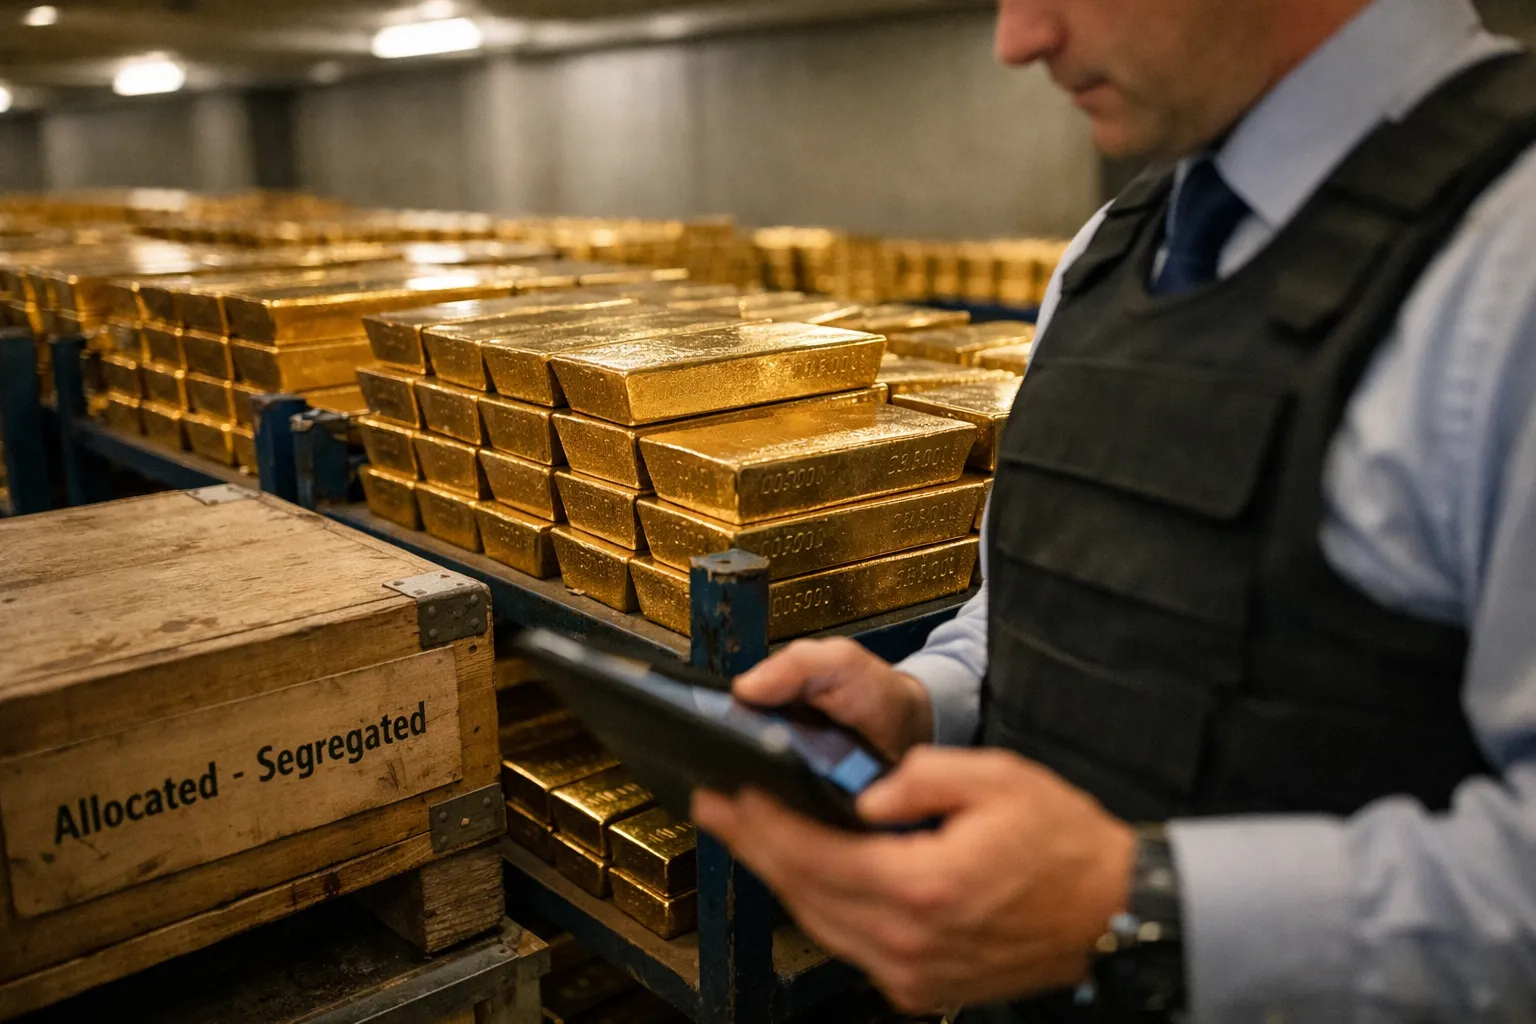
Who: Emerging- and commodity-exporting central banks (notably in Eurasia and the Middle East) and several Asian reserve managers. What: Continued official-sector net purchases of physical gold through the first half of 2026. When: Trends confirmed into July 2026. Where: Pressure is concentrated in London-, Zurich- and Singapore-vaulted kilo and 400-oz Good Delivery bars, with knock-on effects in regional retail markets (U.S., Europe, India, UAE). Why: Reserve diversification, geopolitical hedging and inflation concerns sustain official demand, tightening immediate physical availability and lifting dealer premiums.
Context: why this matters now
Central banks transact at scale and typically buy the same Good Delivery bars and refinery outputs that underpin allocated custody programs and wholesale market liquidity. When official buyers remain active, they absorb inventory that would otherwise serve dealers and private vaulted accounts. That reallocation of physical stock raises the cost and waiting time for private investors seeking allocated metal.
Since the article's original publication in July 2026, market participants report that the pattern has persisted through H1 2026. Dealers and vault operators say the combination of steady official buying, seasonal refinery maintenance schedules in Q2 and elevated demand from retail buyers wary of equity markets has kept convenience premiums and lead times above their 2024–25 norms.
What changed in H1 2026 (updated evidence)
- Official-sector flow remains the dominant physical demand driver. Industry tallies compiled from central-bank disclosures, refiner order books and major dealers show continued net official-sector purchases in H1 2026. While precise public totals vary by source, multiple bullion desks report that official buying accounted for a plurality of net physical demand in the first six months of 2026.
- Premiums widened for small retail sizes. Dealers in London and New York reported that standard 1oz coins and sub-100g bars carried premiums in the 4–7% range above spot in June–July 2026, versus typical 2–4% levels seen in calmer periods. Premiums on kilo bars and 400-oz Good Delivery bars increased more modestly, reflecting where supply pressure is most acute.
- Allocated-delivery lead times lengthened. Major vault operators in London and Zurich advised delivery windows of three to eight weeks for segregated allocated delivery in June 2026, compared with one to three weeks during early 2025. Several refiners temporarily prioritized large institutional orders, extending mint-to-delivery schedules for retail products.
- Geography matters. Singapore and Dubai reported some easing of retail pressure as regional refineries and local mint capacity increased production in Q2, while London and Zurich remained the primary bottlenecks for Good Delivery bar reallocations between official and commercial accounts.
Details and real-world examples
Multiple market participants confirmed operational shifts. For example, a senior operations manager at a large Swiss vault told Gold Investment News in July 2026 that vaults were prioritizing institutional transfers tied to central-bank and sovereign-wealth purchases, which slowed processing of new allocated requests from private clients.
At the dealer level, a U.S. precious-metals retailer reported in early July that orders for 1oz coins spiked after a brief equity-market wobble in late June, compounding the official-sector draw on bullion and prompting temporary caps on order sizes for new customers. Meanwhile, a London-based bullion broker said bank-to-bank transfers of 400-oz bars continued to trade actively, but converting that liquidity into stamped retail bars now takes longer and costs more.
Impact: who is affected and how
- Private allocated holders: Those seeking immediate segregated delivery face longer lead times and potentially higher conversion costs.
- Retail buyers: Small-quantity buyers are most exposed to premium volatility, particularly for coin sizes under 100g.
- ETF investors: Funds such as physically backed ETFs continue to offer a liquidity-efficient alternative; however, in stressed physical cycles ETFs may experience larger-than-usual creation/redemption spreads.
- Refiners and vaults: Operationally, refiners have been extending production runs and vaults have been increasing inbound movements, raising short-term logistics and insurance costs.
Revised practical guidance for gold investors (July 2026)
- Track dealer premium matrices weekly. Given the faster-moving convenience premium, monitor multiple dealers across London, Zurich, Singapore and Dubai. A 1–2 percentage-point swing in premium can materially change the effective entry price for small purchases.
- Re-evaluate physical vs paper allocations. If immediate physical delivery is essential, budget for higher short-term costs and slower conversions. If not, consider maintaining exposure via liquid, physically backed ETFs (e.g., ETFs that publish daily audited holdings) to avoid premium spikes.
- Insist on audited segregated custody for allocated metal. In tight markets, non-allocated or pooled accounts can be harder to convert. Request recent audited statements and clear contractual delivery windows before committing capital.
- Stagger purchases and consider size mixing. Ladder purchases and combine kilo bars (lower premium per ounce) with occasional coin buys if you need retail-sized liquidity.
- Confirm transfer and insurance terms. With elevated vault flows, check counterparty provisions for guaranteed delivery dates, transit insurance limits and potential turnaround fees.
How the market is responding
Refiners and vaults are adapting: several large refiners have announced extended production runs for certain bar sizes and some vault operators expanded evening and weekend processing windows in Q2 2026 to increase throughput. Dealers have also adjusted published premium schedules more frequently, tying increments to live lead-time indicators.
Secondary-market turnover for large bars — the inter-vault market that underpins much of wholesale liquidity — remains functional, but market participants caution that converting large-bar liquidity into coin-sized inventory now carries longer timelines and higher explicit costs.
Reactions from industry and policymakers
In July 2026, spokespeople for major bullion dealers and vault operators emphasized operational constraints rather than structural shortages. A spokesperson at a leading London vault told Gold Investment News: “Inventory is being reallocated toward long-term institutional holders; the system is working but the convenience premium has risen accordingly.” At the same time, a senior economist at a regional central bank (speaking on background) reiterated that official purchases are driven by reserve policy and not by short-term market arbitrage.
What to watch next
- Public central-bank reserve disclosures (quarterly statements). Look for changes in reported gold reserves from the Reserve Bank of India, Kazakhstan National Bank, Turkey’s central bank and other Eurasian and Middle Eastern issuers.
- World Gold Council and industry quarterly demand reports for confirmation of sustained official-sector buying and retail-demand trends.
- Dealer premium matrices and advertised lead times across London, Zurich, Singapore and Dubai.
- Refiner production schedules and vault capacity announcements indicating whether physical supply is expanding to meet demand or if bottlenecks persist into Q3 2026.
Bottom line
As of July 2026, ongoing central-bank purchases remain a meaningful driver of physical gold-market dynamics. For investors who prioritize allocated, segregated ownership, the environment calls for greater attention to premiums, lead times and custody terms. For those focused on short-term exposure to gold’s price action, liquid ETFs and futures continue to offer cost-effective alternatives that avoid the episodic frictions of physical delivery.
How quickly will premiums normalize?
Normalization depends on a combination of reduced official-sector buying, ramped-up refiner output, and vault capacity easing. That could take several quarters; market participants told us to expect episodic premium volatility at least through Q3 2026 unless one of those factors shifts materially.
Is now a bad time to buy physical gold?
Not necessarily. If you value ownership of allocated metal, plan for higher near-term costs and longer lead times — stagger buys and secure audited segregated custody. If you want price exposure without delivery frictions, ETFs or futures remain practical alternatives.
Should I convert ETF holdings to allocated metal given current conditions?
Conversion makes sense only if you require specific-bar ownership and are willing to accept the current convenience premium and lead times. Obtain written delivery or conversion terms from your custodian before initiating conversions.