Overview
The "disconnect" between copper's physical market and its financial curves — tight prompt flows alongside muted or volatile futures premia — persisted through 2026. For commodity traders, allocators and family offices, that gap is not an academic curiosity: it influences arbitrage profitability, financing stress, and multi‑generation wealth planning. This update explains what changed since the original 2025–26 narrative, reviews fresh signals through September 2026, and gives actionable steps for positioning, financing and tax-aware structuring.
Background: how the disconnect has evolved into 2026
The basic anatomy remains unchanged: three ecosystems interact but can move out of sync — (1) mine, smelter and scrap flows that set real-world availability; (2) metal parked in exchange, bonded and private warehouses; and (3) financial demand from ETFs, futures/speculators and structured products. From late 2024 into 2026, structural shifts increased the frequency and amplitude of decoupling episodes. Two themes dominate the recent phase:
- Operational elasticity on the supply side: Chinese secondary refining capacity continued to scale, giving smelters more feedstock options and muting some import demand at the margin — but policy changes and episodic enforcement actions in 2026 created sharper short-term swings in scrap intake than in past years.
- Financial product innovation and leverage: Growth in financed commodity strategies, collateralized OTC swaps, and continued use of ETF share-lending have amplified paper-side flows and the speed at which futures curves react to portfolio rebalancing, sometimes without parallel physical movements.
Data & evidence — what the market has signaled in 2026
- Prompt premia and location tightness: Market reporters and exchange notices through 2026 show repeated episodes where deliverable, prompt-grade cathode and coil inventories tightened in specific hubs (South-East Asia ports, Chilean concentrates corridors, and some Chinese bonded yards). Those localized shortages produced cash premia that were not fully reflected in the nearby futures curve.
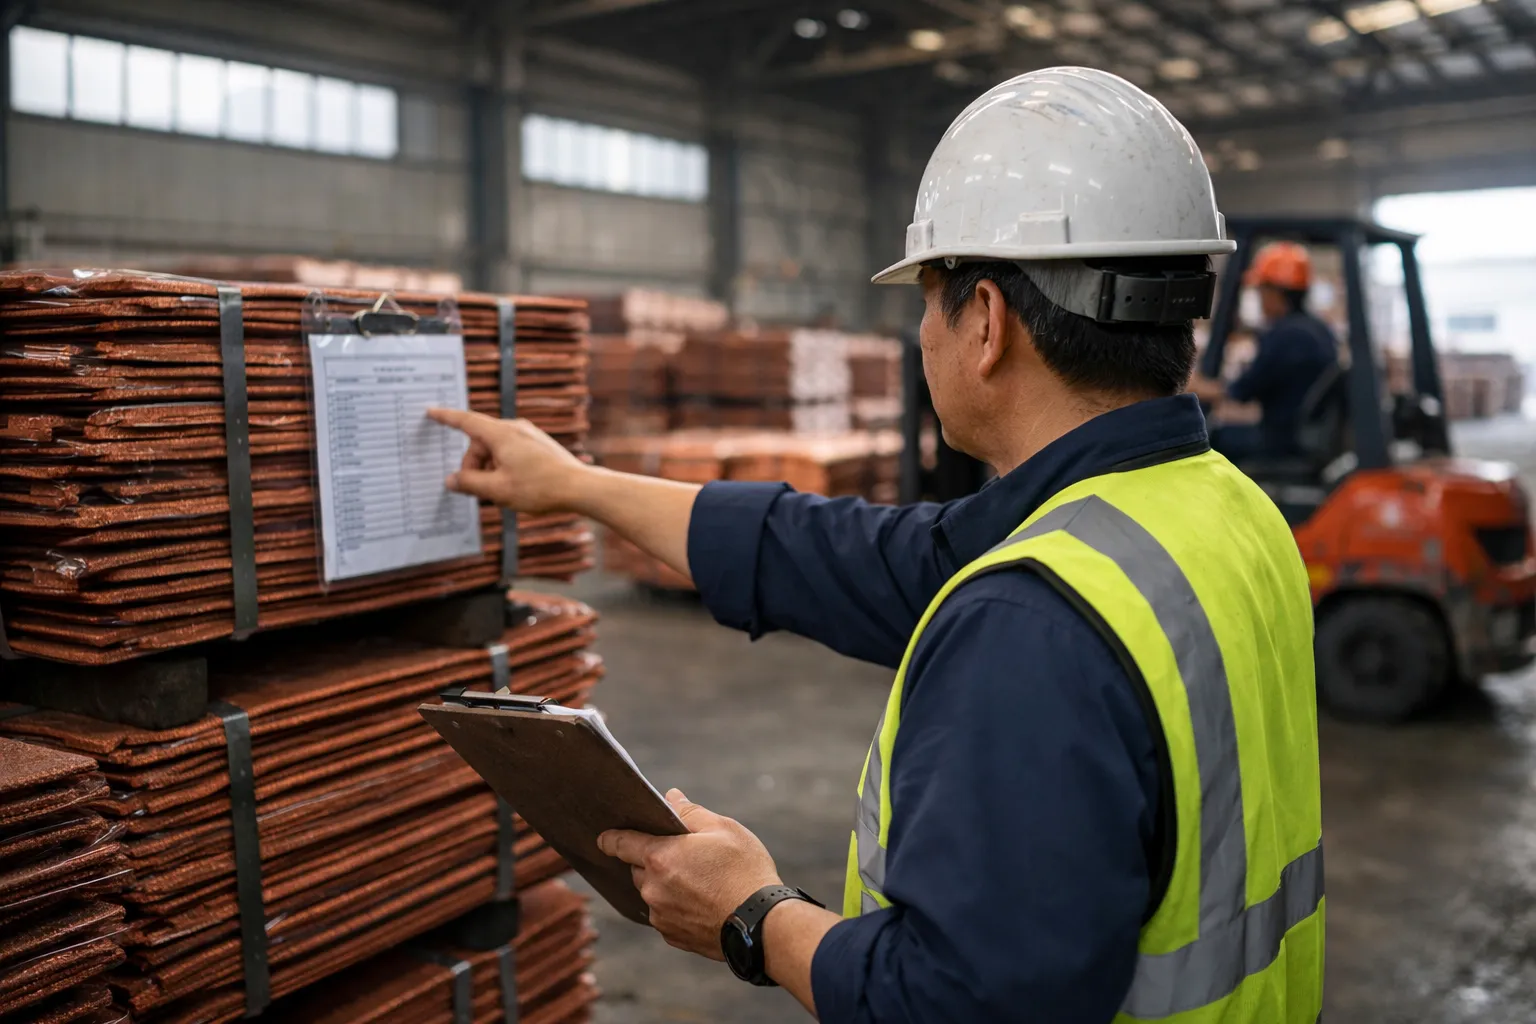
- Exchange stocks vs. marketable flow: Aggregate LME/SHFE headline stocks have been an imperfect gauge. Industry participants increasingly distinguish between "staged" or long-dated warehouse tonnage and truly marketable, immediate deliverables — the latter moved more abruptly in 2026 around port and policy events.
- Financial flows and ETF mechanics: ETF creation/redemption activity and authorized participant behavior remained a rapid source of futures gamma. In 2026, dealers' use of cleared swaps and cross-margining alongside ETF share-lending meant futures positioning could swing materially on relatively modest ETF net flows, producing futures-level volatility disconnected from local physical tightness.
- Freight, logistics and permit optics: Shipping route congestion, vessel availability and national permit cycles continued to shape where and when metal became deliverable. Market intelligence providers and AIS vessel-tracking proved increasingly valuable to those arbitraging location spreads.
Multiple perspectives
Different market participants experience the disconnect differently:
- Physical traders and smelters: Operators point to greater optionality from scrap and secondary metallurgy as a structural buffer — but they also report shorter policy-driven windows for bonded yard draws and more punitive customs inspections in some jurisdictions during 2026, increasing the volatility of prompt supply.
- Financial desks and prop trading: Quant teams emphasize faster, more concentrated flows in paper markets, driven by concentrated ETF positions and the continued rise of leveraged, collateralized strategies that can create waterfall reactions on margin calls.
- Long-term allocators and family offices: These investors value liquidity and tax efficiency. Many prefer layered exposure — a liquid paper sleeve for tactical moves and selective physical or private‑market allocations to capture structural premia and to hedge against multi‑year supply shocks.
- Tax and legal advisers: U.S.-based counsel remind clients that Section 1256 tax treatment for futures remains an important lever for short‑term programs, while physical metal ownership implicates inventory accounting, ordinary income rules for dealers, and estate-transfer considerations for inheritors.
Why the disconnect matters now
Two practical consequences sharpened in 2026:
- Basis and location spreads are now a primary alpha source: With paper markets capable of rapid re-pricing, traders with logistics capabilities captured outsized returns from cross-dock arbitrage and regional repositioning. Those without operational access saw higher volatility and slippage when trying to replicate these returns synthetically.
- Financing complexity increased: Lenders and prime brokers applied tighter haircuts and more granular covenants to metal-collateralized financing. Where financing tightened, previously attractive cash-and-carry trades could become uneconomic quickly, and margin squeezes amplified forced selling in the paper market.
Updated trading approaches — what to change in 2026
Below are three refined approaches that reflect 2026 market realities, with practical steps and risk controls.
1) Enhanced cash-focused carry and warehousing
Refinement: Add dynamic covenant stress-testing and multiple funding lines. Use shorter warehouse tenures and staggered delivery windows to reduce exposure to sudden backwardation.
- Operational add-ons: contractual soft clauses for customs delays; multiple bonded locations to shift tonnage quickly.
- Risk control: stress test carry P&L under higher financing costs and partial delivery failures.
2) Location and prompt-premium arbitrage with AIS-led intelligence
Refinement: Combine real‑time AIS shipping data, local port intake reports and bonded yard release notices to time cross‑border moves. Favor trades where logistics time arbitrage exceeds break‑even financing and customs costs.
- Edge: pay for high‑frequency local intelligence (port call manifests, smelter intake schedules).
- Risks: FX, customs reclassification and sudden policy reversals remain the principal threats.
3) Paper-driven volatility and tail-hedged strategies
Refinement: Use options and structured overlays to capture paper volatility while hedging against a rapid physical squeeze. Consider vertically structured products that replicate carry without requiring metal custody.
- Risk control: buy protective options where naked futures exposure is required; size positions to withstand tidal ETF flows.
- Operational note: ensure counterparties can meet delivery obligations or have clear substitution clauses.
Tax, wealth transfer and portfolio considerations (U.S.-focused, updated)
- Futures remain tax-efficient for frequent traders: Section 1256 treatment (60/40 capital gains split) continues to be a core reason active U.S. traders prefer futures over physical for high-turnover strategies. Confirm current IRS guidance and reporting mechanics before program launch.
- Physical holdings and estate planning: For multi‑generation exposure, direct physical ownership requires operational governance: entity choice (LLC or trust), clear succession rules for custody access, and appraisal mechanisms. Physical metal as a family-asset class raises liquidity needs at death — plan for potential forced sales and estate tax implications.
- Using private-market vehicles: Increasingly, high-net-worth allocators use private metal‑backed yield products or long-dated storage structures to capture basis; evaluate counterparty credit, storage insurance, and transferability on death.
Practical checklist — what traders and allocators should do now
- Prioritize deliverable tonnage, not just headline stocks: Track prompt warrants and bonded yard release notices rather than aggregate exchange inventories.
- Instrument financing resilience: Secure multiple funding sources, build stress scenarios that assume rapid margin calls, and negotiate contingency release clauses with warehouses.
- Use real-time logistics data: Integrate AIS tracking and local intake reports into execution algorithms for location spreads.
- Layer exposures: Combine liquid paper positions (for tax and rebalancing flexibility) with selective physical or private metal allocations for structural alpha and estate planning.
- Tax and entity alignment: Coordinate trading program choice (futures vs. physical) with entity structure, tax strategy and wealth-transfer goals; involve tax counsel early.
Outlook — what could re-synchronize paper and physical?
The same four scenarios highlighted in earlier analysis remain relevant in 2026, but their probability and timing are dynamic:
- Demand surge: A clear acceleration in electrification rollout or major infrastructure programs could lift both spot and futures simultaneously.
- Supply shock: A material, prolonged outage at a large mine or smelter could force sharper backwardation and compress ETF and futures positions as market participants scramble for delivery-grade metal.
- Policy inflection: Chinese import, scrap or bonded-yard policy changes could flip the marginal supply quickly — these remain the single biggest near‑term re‑synchronizers.
- Liquidity regime shift: A reset in global funding costs or a major change in dealer balance-sheet capacity would alter how paper positions convert into physical demand.
For allocators thinking decades, the practical take-away is consistent: retain liquidity and tax-efficient sleeves for strategic rebalancing, but allocate a measured physical/private-metal component when you can access reliable custody, financing and succession planning. Those structures can preserve purchasing power across cycles and provide optionality when paper markets decouple.
Frequently asked questions
Why do futures sometimes ignore clear local cash shortages?
Futures are a global, fungible price discovery mechanism reflecting marginal supply/demand and portfolio flows. If paper-side liquidity is abundant and dealers absorb ETF rebalancing, futures may not show sustained backwardation even when certain delivery hubs face prompt tightness — especially when that tightness is short‑lived or localized.
Can retail investors capture prompt-premium arbitrage?
Direct arbitrage on prompt premia requires operational access (bonded warehousing, logistics, customs clearance) and financing — typically beyond retail reach. Retail investors can gain directional exposure with futures or options or access physical exposure via specialized funds and private placements, but pure location arbitrage is largely institutional.
How should I structure multi-generational copper exposure?
Start with a clear objective: income, inflation hedge, or capital appreciation. For most families, a blended approach—liquid ETFs/futures for tradability and tax efficiency, plus a dedicated physical or private‑market tranche under an entity designed for succession (LLC or trust with defined transfer rules)—balances operational complexity and inheritance realities. Legal and tax counsel are essential.
What immediate data points should I add to my daily dashboard?
In addition to exchange headline stocks, add (1) prompt warrant counts and release notices; (2) bonded yard release filings in key hubs; (3) AIS shipping flows into major ports; (4) Chinese scrap intake reports and Customs notices; and (5) ETF creation/redemption activity and large OI changes in nearby futures.
— David Park, Real Estate & Tax Correspondent. This update synthesizes industry exchange notices, market-structure developments through September 2026 and market practitioner input; it is analytical and not investment or tax advice. Consult your professional advisers when applying strategies to specific circumstances.