Who: individual and institutional gold investors. What: a refreshed playbook of nine practical rules for owning gold as of July 2026. When: July 2026 — markets and market structure moved measurably since June. Where: global retail and institutional gold markets, with emphasis on the U.S., EU, India and major Asia-Pacific hubs. Why: premium behavior, custody disclosures, and regulatory guidance have changed; failing to adapt can quietly erode returns.
Context: why re-up these rules in July 2026?
Gold remains a core hedge and portfolio diversifier, but the market’s plumbing — custody models, buyback mechanics, and regional premium behavior — is where returns are won or lost today. Since June, three shifts matter: (1) renewed central-bank demand through H1 2026 has kept baseline spot elevated; (2) vault and custody reforms pushed by the London Bullion Market Association (LBMA) and picked up by major custodians have altered redemption timelines; and (3) rapid expansion of tokenized “digital gold” products has widened counterparty complexity. These are not theoretical changes — they alter the all-in cost and the speed at which you can convert metal to cash.
Details: What’s new — and what to actually change
1. All-in cost matters more than ever
Spot price is still the lingua franca, but your return is spot minus practical costs: premiums, shipping, assay/verification, VAT/sales tax, and buyback discounts. As of July 15, 2026 spot gold traded in the low $2,300s/oz; that headline matters less than the 1.5–4.0% range in all-in transaction frictions you’ll likely see depending on SKU and market. Action: maintain a live “all-in” worksheet (spot + premium + delivery + tax + payment fees + expected buyback discount) for every buy and decline purchases where the worksheet shows negative expected profit after a realistic 6–12 month hold.
2. Physical vs. paper: choose risks deliberately
More tokenized and “allocated but pooled” products launched in H1 2026. These lower storage hassle but can lengthen and complicate redemptions. The updated rule: explicitly list which counterparty risks you accept and why. Practical moves: split exposure (60/40 physical/paper if you prioritize possession, 40/60 if you prioritize tradability) and demand written redemption timelines for paper products — not marketing copy but legal T&Cs with dispute resolution clauses.
3. Premiums are hyper-local and faster
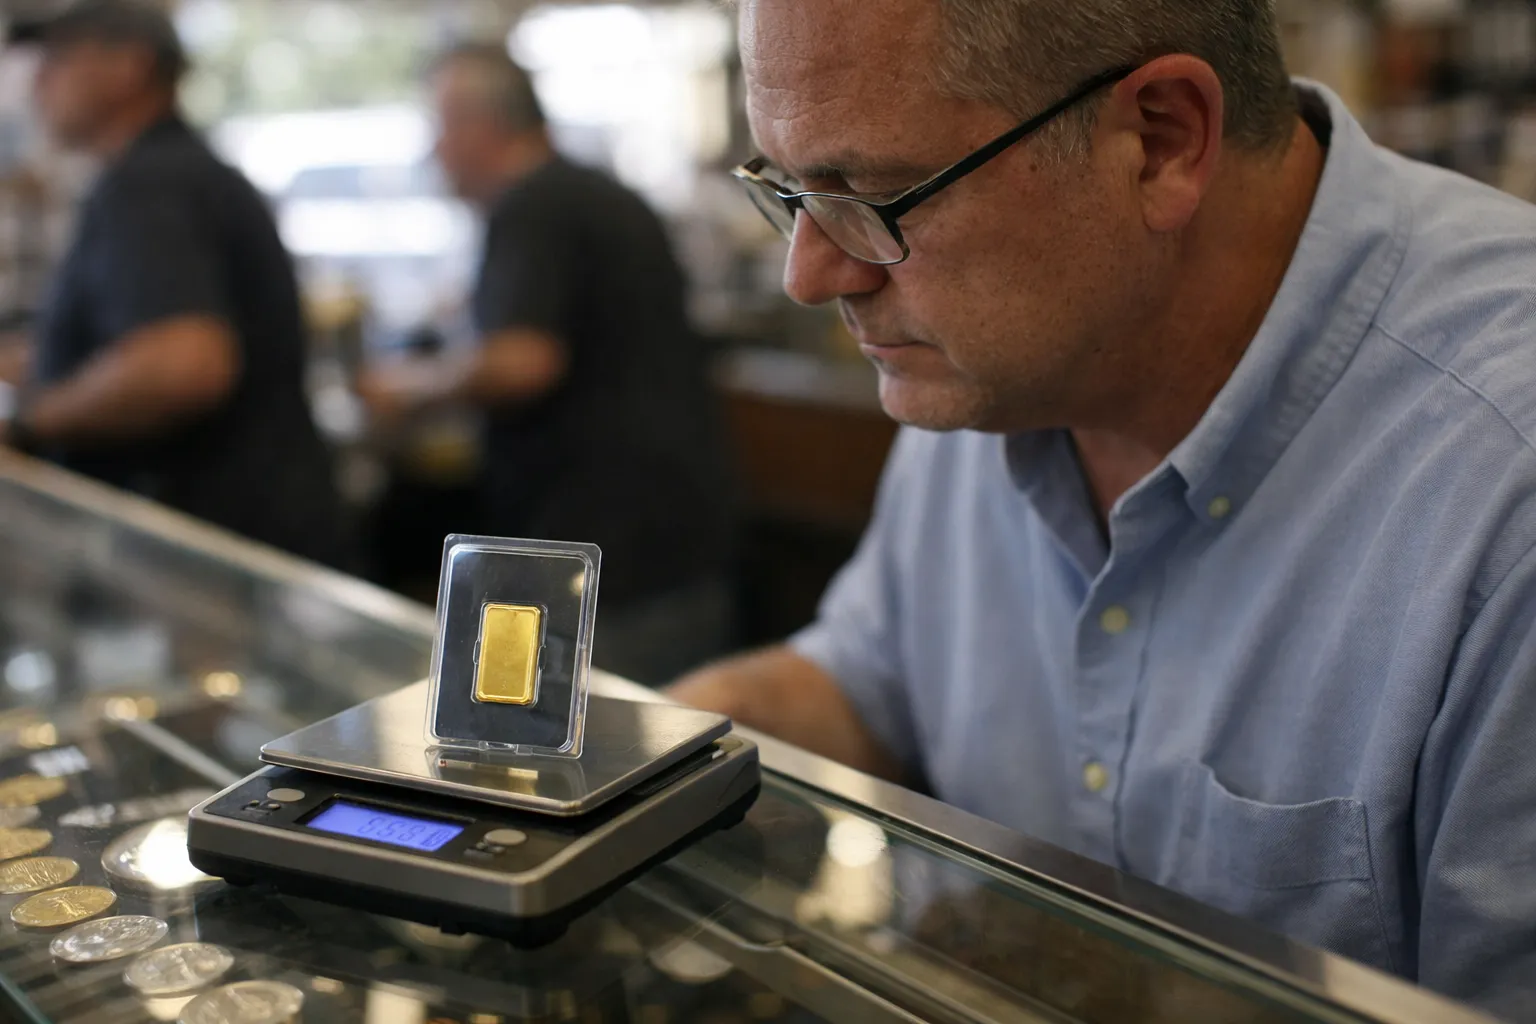
We saw acute regional premium swings in June—examples: Mumbai and parts of India saw premiums widen by roughly 60–150 rupee per 10g during local demand bursts; Singapore dealers moved premiums 20–40 basis points overnight in response to shipping congestion. If you buy online from a dealer in one state and sell in another metro, don't assume parity. Immediate move: before you buy, phone two prospective buyers in your local market and ask their buyback price for the exact SKU and serial you plan to buy.
4. Liquidity testing is mandatory, not optional
“I can sell anytime” is not a plan. With longer redemption windows for some custodial platforms and stricter AML/assay checks at secondary dealers, the difference between “can sell” and “can sell quickly at a fair price” widened in H1 2026. Updated practice: quarterly liquidity tests — submit buyback inquiries, confirm required documentation (assay cards, serials), and time the round-trip. Keep receipts and serials digitized and backed up in at least two secure locations.
5. Don’t confuse collectibility with resale math
Commemorative issues continue to command high retail premiums but limited secondary markets. If your objective is wealth preservation, favor low-premium, widely recognized bullion SKUs (e.g., sovereign coins or 1oz bars from widely traded refiners). Treat collectible purchases as a separate, speculative sleeve and price them for likely retail-to-retail sale, not for instant liquidity.
6. Rebalance mechanically, not emotionally
Set a target allocation and a rebalancing band (example: ±15–25% of target). Given the persistence of macro-driven rallies in early 2026, mechanical rebalancing prevented both panic buys in March and forced sales in May for many disciplined investors. Use limit orders for paper positions and staged physical buys to avoid paying spikes in premiums.
7. Tax reality: your position isn’t real until it’s after-tax real
Tax treatment continues to vary by jurisdiction and product. EU VAT rules remain SKU-specific; India’s GST on precious metals remains a material drag for small-scale retail buyers. Updated step: start a lot-level log for every purchase — date, SKU, weight, price, premium, total cost, seller, payment method, storage location — and consult a tax advisor about capital gains vs. collectibles treatment in your country before executing large buys.
8. Redundancy beats convenience
Relying on a single app or single custodian is convenient until access matters. Build two liquidity paths and two storage assumptions: one for “organized exit” and one for “fast access.” For example, hold a portion in allocated storage you can take possession of within a week and another portion in a reputable allocated ETF or brokerage-backed holding you can liquidate through normal market hours.
9. Write the one-paragraph plan you will follow under stress
Successful gold investors make rules they’ll execute when markets get noisy. Write: when I buy (trigger), how much I buy (size), where I hold it (format), and when I sell (exit trigger). Keep it short, specific and non-emotional — and review it after every quarter.
Impact: who this affects and how
Retail stackers who ignore all-in costs and exit pathways will see nominal gains eaten by premiums and buyback discounts. Wealth managers must document redemption paths for clients and be prepared to explain custody models. Institutions should demand transparency on segregation versus pooled allocations and test operational claims — the LBMA-led vault disclosure changes implemented this spring increased reporting but also clarified differences between full segregation and pooled allocated structures.
Reactions: industry voices to watch
World Gold Council (WGC): continues to be the best source for flow and demand data; their mid-year 2026 flow brief (July 2026) highlights sustained central-bank buying as a structural support.
Major dealers (APMEX, Kitco, MKS PAMP): now publish temporary buyback guidance and clearer assay-return policies during supply shocks. Use dealer policy pages as a liquidity scoreboard.
What’s next: timelines and watchpoints
- Watch central-bank announcements and WGC monthly flow notes through Q3 2026 — central-bank demand remains the structural floor.
- Track regional premium spreads weekly — call two local dealers before every major buy.
- Expect continued product innovation — more insured delivery options and tokenized allocation products will arrive; read redemption and custody fine print before committing funds.
FAQ: Quick answers for common headaches
How should I split physical versus paper holdings?
No universal split fits everyone. A practical starting point: 60/40 physical/paper if you value possession and control; 40/60 if you prioritize tradability and lower immediate transaction costs. Whatever split you choose, document redemption mechanics for paper holdings and ensure physical storage and insurance are in place.
What records do I need to keep?
Keep a lot log: date, item description (SKU or serial), weight, purchase price, premium, seller, payment method, storage location, and supporting receipts. Digitize and back up this file. For estates and taxes, organized records materially reduce friction and cost.
How often should I test liquidity?
Test quarterly if you are actively allocating; at minimum, test before any sizable buy and annually if your allocation is static. Testing means calling buyers, noting buyback quotes and documentation requirements, and timing the process from inquiry to settlement.
Is premium worth paying for new retail products?
Pay a premium only if it buys concrete benefits: demonstrable local liquidity, easier divisibility, or collectible value you reasonably expect to realize. Otherwise, favor low-premium, widely recognized bullion SKUs.
One final takeaway?
Gold still works as a diversifier and hedge — but in mid-2026 the win is in the details. Discipline, paperwork, and a clear liquidity plan will outperform loud macro calls every time. If you do one thing this week: call two buyers in your market and confirm the buyback price for the exact SKU you own or plan to buy.