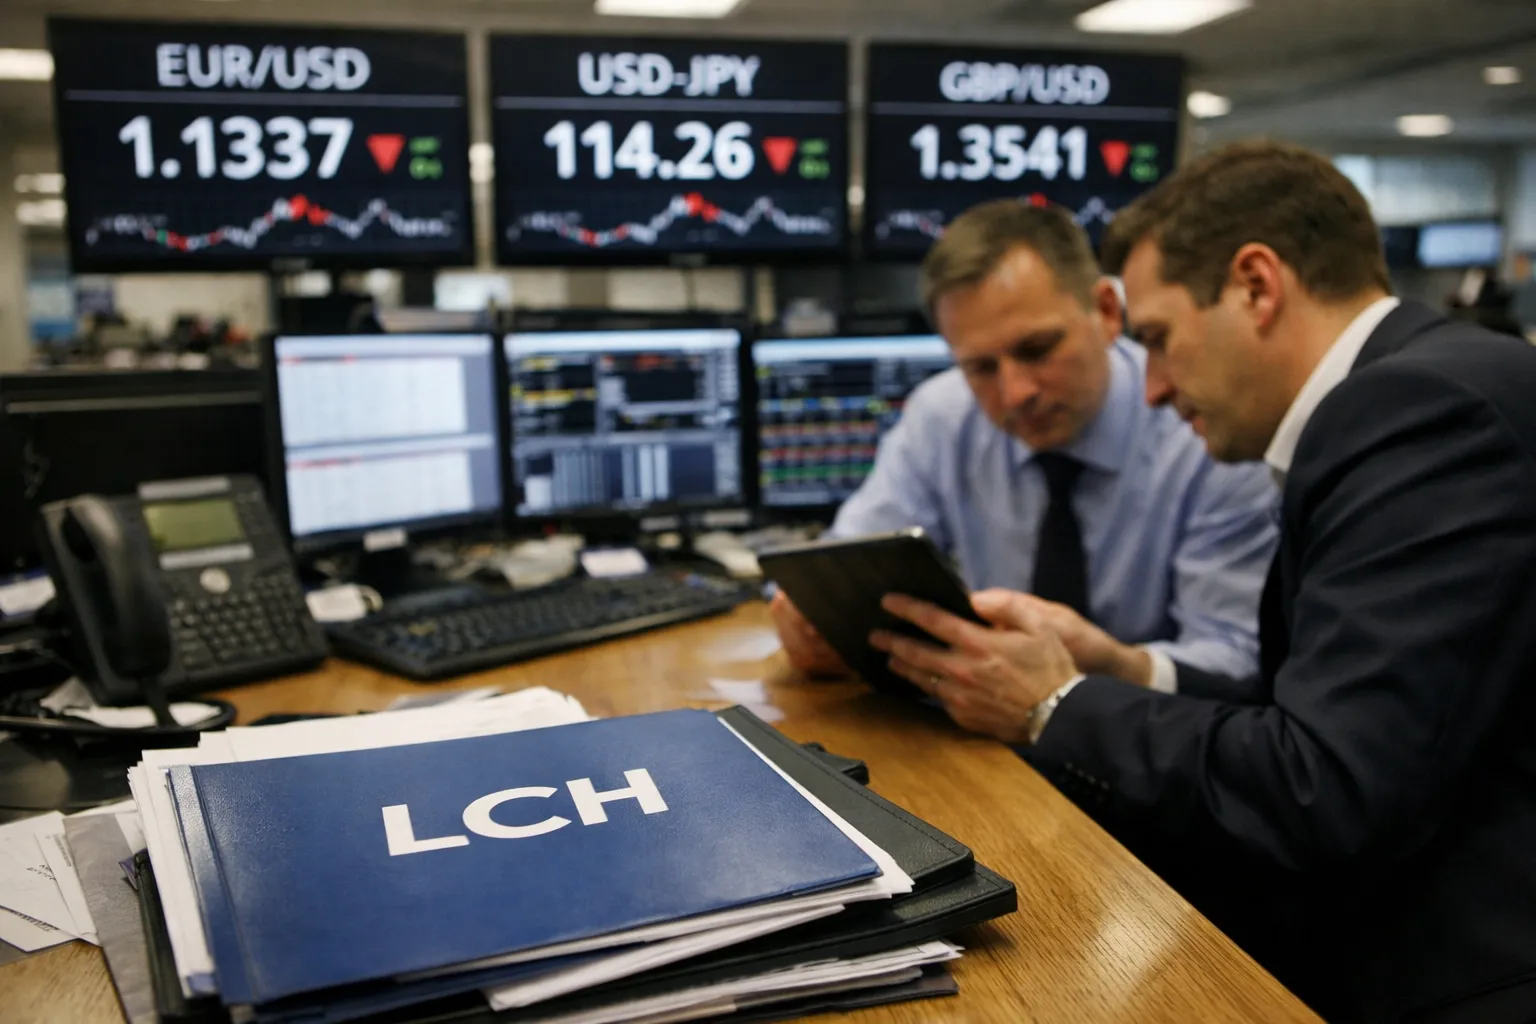
London — LCH, the derivatives clearing house owned by London Stock Exchange Group, has launched a pilot program for centrally cleared foreign-exchange swaps in August 2026 aimed at moving a portion of G10 FX‑swap flow from bilateral channels into central clearing. The initiative, announced to market participants this month, signals an important shift for the historically OTC and bank‑intermediated FX‑swap market.
What the pilot covers
The pilot initially targets short‑dated FX‑swap products among the four most traded deliverable pairs — USD/EUR, USD/JPY, EUR/GBP and GBP/USD — with a planned phased expansion to additional G10 crossings. According to materials circulated to prospective members, the pilot will support standard FX‑spot/forward roll‑over structures with maturities from overnight to three months and will use margining and porting mechanisms similar to those deployed for cleared interest‑rate swaps.
LCH is positioning the pilot as a way to reduce bilateral counterparty exposure and to provide centralized margining efficiencies for dealers and large buy‑side firms that execute high volumes of short‑dated FX swaps for funding, hedging and balance‑sheet management.
Settlement and interoperability
- Clearing model: novation to LCH with initial margin (IM) and variation margin (VM) calculated at the clearing house level.
- Settlement: LCH intends to rely on existing settlement rails for FX — including commercial bank settlement and links to payment-versus-payment (PvP) utilities — to avoid re‑engineering end‑to‑end delivery mechanics.
- Portability and default: LCH says default management will follow its established playbook for netting and auction processes, with contingency provisions tailored to FX‑specific settlement windows.
Why clearing FX swaps matters
FX swaps are the backbone of global dollar funding and intraday liquidity management. They are used by banks, asset managers and corporates to roll short positions, hedge currency risk and manage cross‑currency funding. Traditionally, most of this activity has been conducted on a bilateral basis between dealer banks and their customers or routed through prime brokers.
Centrally clearing FX swaps could bring three practical benefits:
- Counterparty risk reduction via multilateral netting, lowering aggregate exposures between participants.
- Consolidated margining that can reduce total initial margin requirements across cleared portfolios versus a patchwork of bilateral IM agreements.
- Operational standardization and transparently defined default procedures that could reduce systemic contagion risk in stress events.
Market reaction — cautious optimism
Market participants contacted by Forex Trading Daily welcomed the potential risk reduction but flagged several operational and liquidity questions.
Several major dealers said they will join the pilot as clearing members or via sponsored access to evaluate real‑world margining outcomes. “For desk-level hedging and short-tenor funding, centralized clearing can materially change balance‑sheet economics,” one European bank source said on condition of anonymity. “But success depends on settlement integration and how much notional flows through the central book without fragmenting liquidity.”
Buy‑side participants and hedge funds expressed interest in margin efficiencies, but some noted potential increases in direct costs. “For smaller asset managers that rely on dealer-owned prime brokerage, the need for membership or sponsor relationships could make access more complex,” a multi‑manager head of FX noted. “We’ll be watching onboarding, margin add‑backs and the pricing for cleared versus bilateral swaps.”
Implications for prime brokers and liquidity providers
Prime brokers and bank liquidity providers should expect structural adjustments if the pilot scales. Central clearing migrates counterparty exposure away from bilateral credit lines, which could reduce demand for prime‑broker balance‑sheet and affect internal funding models that currently profit from handling client FX‑swap flow.
Conversely, clearing could open new avenues for non‑bank liquidity — including electronic market makers and central limit order books — if a cleared product reduces counterparty‑credit frictions. How quickly such secondary liquidity emerges will depend on margin economics and the cost of routing trades into the cleared stack.
Regulatory lens and systemic considerations
Regulators have long sought ways to contain the systemic risks posed by unsecured interdealer FX exposures. Central clearing has been a recommended tool post‑2008 for interest‑rate and credit products; extending clearing to a sizeable portion of FX swaps addresses similar counterparty concerns. That said, supervisors will be focused on settlement‑related tail risks — in FX, default management must reconcile both cleared positions and hard settlement timing across currency rails.
LCH has told members it will engage closely with payments utilities and central counterparties to ensure settlement-waterfall clarity during defaults. Market observers said regulators will expect rigorous testing of porting and auction procedures under stressed settlement scenarios.
Next steps and what traders should watch
- Onboarding timeline — LCH will run the pilot through the autumn, with live trading windows and staged capacity increases. Traders should track membership timelines and operational readiness dates.
- Margin outcomes — initial margin models and cross‑product netting assumptions will be published to pilot participants; differences versus bilateral IM levels will guide participant economics.
- Settlement integration tests — success hinges on smooth PvP or equivalent settlement integration across USD, EUR, JPY and GBP rails.
- Liquidity footprint — watch dealer ticketing and spreads as participants divert selected tenor flows into the cleared pool; intraday depth and midday roll markets will be an early indicator.
For FX trading desks, the LCH cleared FX‑swap pilot represents both an operational challenge and a possible strategic opportunity. If margin efficiencies and robust settlement mechanics are achieved, the pilot could reframe how short‑dated funding and hedging are executed in G10 currencies — with knock‑on effects for liquidity providers, prime brokers and treasury desks.