Overview
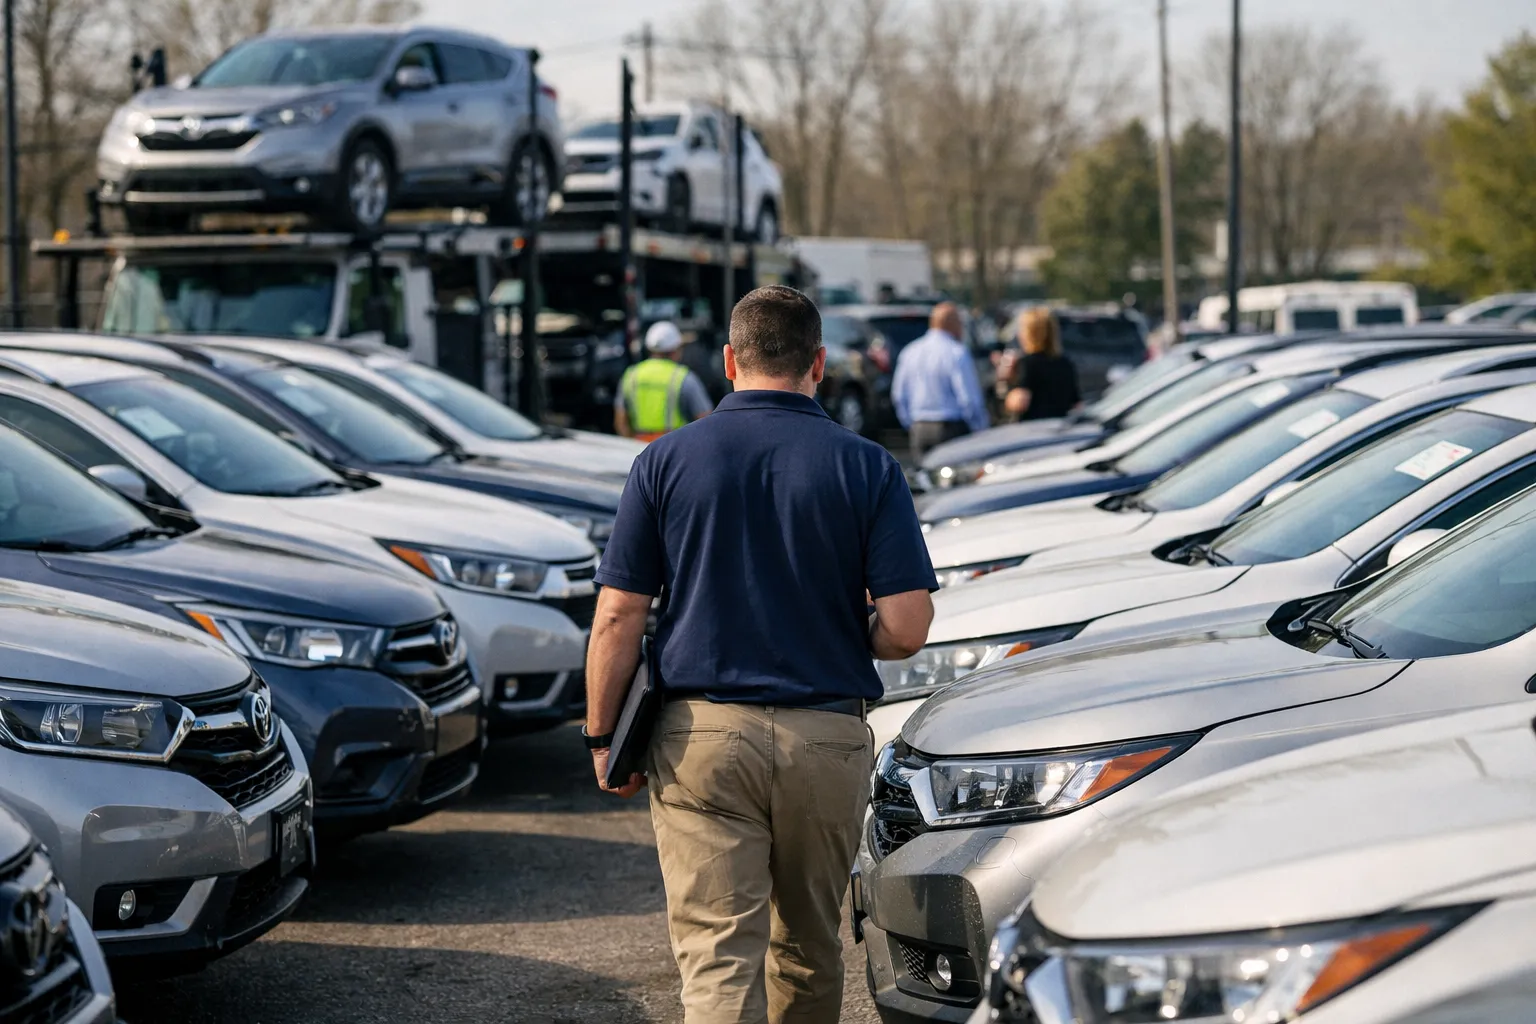
The concentrated return of 2019–2021 leases—what the industry calls the “off‑lease wave”—is the defining force in the summer 2026 used‑car market. For car‑buying enthusiasts this matters because supply is changing at the model, metro and channel level in ways that create both sharper bargains and new risks. This update summarizes what’s unfolded through mid‑2026, what the data and industry sources are showing, and the concrete tactics that put you in control when buying a 2–4‑year‑old vehicle.
Background: Why this wave exists and why timing matters
Two factors set the stage. First, the lease boom of 2019–2021—driven by aggressive OEM lease incentives and constrained new‑car deliveries—front‑loaded many short (36–39 month) contracts. Second, leases typically return en masse at term, so the 2019–2021 cohort concentrated returns in 2025–2026 instead of spreading them out. That concentration amplifies ordinary supply shocks: rather than a steady trickle of trade‑ins and single‑owner listings, large blocks of near‑new vehicles flow through remarketing channels over months.
Since July 2026 brings the highest visible density of those returns, short‑term market dynamics (auction pricing, dealer lot saturation, and local listing glut) matter more than national averages. Readers should treat “local” as the operative unit: metro listing counts, dealer days‑to‑turn and auction lanes tell the story better than a single national number.
Data and evidence through mid‑2026
Industry channels and marketplace metrics consistently point to increased availability and softer pricing for specific segments:
- Wholesale pressure: Major remarketers and wholesale networks reported higher lane volumes in H1 2026. Manheim and other auction channels noted elevated off‑lease units on auction blocks in Q1–Q2; dealers with scale used that volume to restock retail lots, amplifying retail competition.
- Segment concentration: Compact and mainstream SUVs (Toyota RAV4, Honda CR‑V class), entry luxury SUVs (Lexus NX, BMW X1/G02), and luxury compact sedans (BMW 3‑series, Mercedes‑B‑class equivalents) dominate returned volumes. Those segments are showing the largest absolute increases in 2–4‑year‑old listings on OEM CPO pages and third‑party marketplaces.
- Regional variation: Sunbelt metros (Phoenix, Dallas, Atlanta, Miami) are absorbing more units due to population growth; coastal dense markets with limited dealer space (San Francisco Bay Area, Boston) show sharper local listing spikes and quicker local markdowns.
- EV and hybrid behavior: Used EVs and plug‑in hybrids have split into two camps. High‑demand, well‑known models (most Tesla variants, some high‑range Hyundai/Kia EVs) are holding value better, while older PHEVs and early mainstream EVs are more price‑sensitive because of buyer concerns about remaining battery life and warranty coverage.
Quantitatively, dealers and brokers we surveyed in July 2026 report typical retail markdowns for the most affected 2–4‑year SUVs in target metros in the range of about $1,500–$3,000 from peak demand pricing earlier in the decade—an average that varies widely by trim, mileage and region. Where dealers can buy multiple units from auctions or captive-recaptured lease pools, competition drove even larger retail incentives in late spring.
Multiple perspectives from the market
Dealer groups: Large multi‑franchise dealers see this as an opportunity. They favor volume buys at auction, push CPO certification selectively, and use short‑term financing deals to convert inventory. Their view: higher supply is offset by scale and flexible pricing.
Independent dealers and small lots: Smaller operators report thinner margins and selective buying: they avoid units showing rental history or higher mileage and focus on niche trims where they can differentiate.
OEM remarketing teams: Several OEMs have publicly adjusted CPO intake plans this year—some expanding certification throughput to move inventory quickly, others temporarily throttling CPO intake where inspection capacity is constrained. The result is spotty availability of CPO units by brand and region.
Buyers and analysts: Consumer advocates recommend patience and due diligence; market analysts highlight that while wholesale price declines have been clear, retail prices lag and the timing of downward pressure varies regionally. That creates arbitrage opportunities for buyers willing to hunt across metros or use dealer brokers to access auction-sourced units.
Implications for buyers—updated tactics for July 2026
The core playbook from earlier in 2026 still applies but with refinements based on recent developments:
- Watch metro‑level inventory, not national headlines: Use search filters on multiple marketplaces to track listing counts and days‑to‑sell for your target model in several metros. If your local market shows a spike, broaden your search to nearby metros with lower inventory for possible arbitrage.
- Exploit short windows after auction waves: Dealers that buy at auction often list those cars quickly at thin margins. If a large auction haul was reported in your region in the past two weeks, expect competitive retail listings and small negotiable cushions in the following 2–8 weeks.
- Prioritize CPO for EVs and PHEVs: Certification and battery warranties materially affect resale value and risk. For plug‑in vehicles, insist on remaining battery warranty duration and request detailed battery health reports when available.
- Be selective on rental-channel units: Vehicles that passed from lease to rental then back to retail require closer inspection for service records, unusual wear and towing or heavy‑use history. Ask for full vehicle history and consider a professional pre‑purchase inspection even when buying CPO.
- Timing is tactical: Prices have tended to soften in discrete pulses as batches flow through auctions. If you can wait 4–12 weeks after a local inventory spike, you may gain negotiating leverage. Conversely, if the unit you want is rare (specific trim or color), acting quickly can be better than waiting for broader softening.
- Cross‑market transport math: Shipping a bargain from another metro still makes sense for savings greater than the combined transportation, tax, and registration delta. Use calculators that factor state sales tax differences and transport quotes before committing.
Fresh examples and real‑world context
Case: In June 2026 a multi‑dealer group in Phoenix bought a 150‑unit block at a regional sale that included 2022 compact SUVs and 2021 luxury compacts. Within three weeks they listed a subset with $1,500–$3,000 discounts vs. earlier 2025 retail pricing; demand soaked up many units but LTV buyers prioritized low‑mileage, well‑spec’d cars and pushed higher‑mileage units into deeper discounting.
Case: A coastal Bay Area dealer reported rapid local listing increases for compact luxury sedans in late spring; with limited lot space that market saw the quickest visible retail markdowns—buyers who expanded searches to nearby inland metros found equivalent cars for less when transport costs were included.
Risks to monitor
- Quality dispersion: Higher volume returns means wider variation in condition. Inspection and record checks are essential.
- Dealer and CPO policy changes: OEMs may change certification thresholds or incentives mid‑season; keep an eye on brand communications and local dealer stock.
- Financing volatility: Changes in interest rates and credit flow can re‑shape demand quickly; watch prevailing used‑car finance rates when planning timing.
Outlook: What to watch next (July–December 2026)
Over the next 6 months the market will likely show continued regional heterogeneity. Key indicators to monitor:
- Weekly wholesale lane volumes and Manheim/Cox Automotive commentaries: sustained elevated volumes imply continued retail pressure; a drop signals absorption and potential stabilization.
- OEM CPO intake updates: if manufacturers throttle certification, short‑term retail supply could tighten and push premiums back up for certified units.
- Interest‑rate trajectory: easing could draw price‑sensitive buyers back into the market; persistent tight credit keeps downward pressure.
For car‑buying enthusiasts this likely means continued opportunities to find near‑new vehicles at reduced premiums—provided you adopt metro‑level scouting, insist on inspection and warranty coverage for EVs and hybrids, and time purchases to local supply cycles.
Practical short checklist (what to do right now)
- Set alerts on 2–4 marketplaces for your target model across 2–4 metros.
- Compare local dealer retail, CPO listings and open‑market auction prices (via broker) before bidding or negotiating.
- Prioritize CPO or third‑party extended warranties for EV/PHEV purchases; request battery health data.
- Factor transport, taxes and registration when considering cross‑market purchases; get a transport quote first.
- Require a professional PPI (pre‑purchase inspection) for any non‑CPO unit and verify full service history.
FAQ
Will the off‑lease wave make all used cars cheaper?
No. The effect is concentrated by age, segment, trim and metro. 2–4‑year‑old compact and mainstream SUVs and many entry luxury models are seeing the most downward pressure. Rare trims, low‑mileage examples, and high‑demand EVs remain resilient.
Is now the best time to buy a used EV?
Potentially—if you prioritize certified units with battery warranties. Values for mass‑market EVs vary widely by model and remaining battery coverage. For older or out‑of‑warranty EVs, factor potential battery replacement or lower range into the total cost of ownership.
Should I buy my leased car at buyout now?
Compare your contract buyout to current retail and recent auction realizations for similar vehicles. In many metros, market prices for comparable examples have fallen; if buyout is above contemporaneous market value, buying and reselling privately may not be the best financial move.
How much can I negotiate off asking prices on 2–4‑year‑old SUVs?
Negotiable amounts vary by market and timing. In many affected metros in mid‑2026 we observed typical dealer room of $1,000–$3,000 on popular compact SUVs—more for higher‑mileage or rental‑history units. Use multi‑market comparisons and recent sale comps to set your target.
What red flags should make me walk away?
Missing service records, inconsistent mileage history, evidence of heavy rental or commercial use that isn’t disclosed, and a vehicle failing a professional inspection are all legitimate reasons to decline a purchase—no bargain is worth durable mechanical or title risk.
Bottom line: The 2026 off‑lease wave is producing clear opportunities but not uniform bargains. The winning strategy is metro‑level surveillance, a willingness to shop across channels and regions, and rigorous inspection discipline—especially for EVs and vehicles with rental histories. With those practices, enthusiasts can find near‑new cars at materially reduced premiums in the coming months.