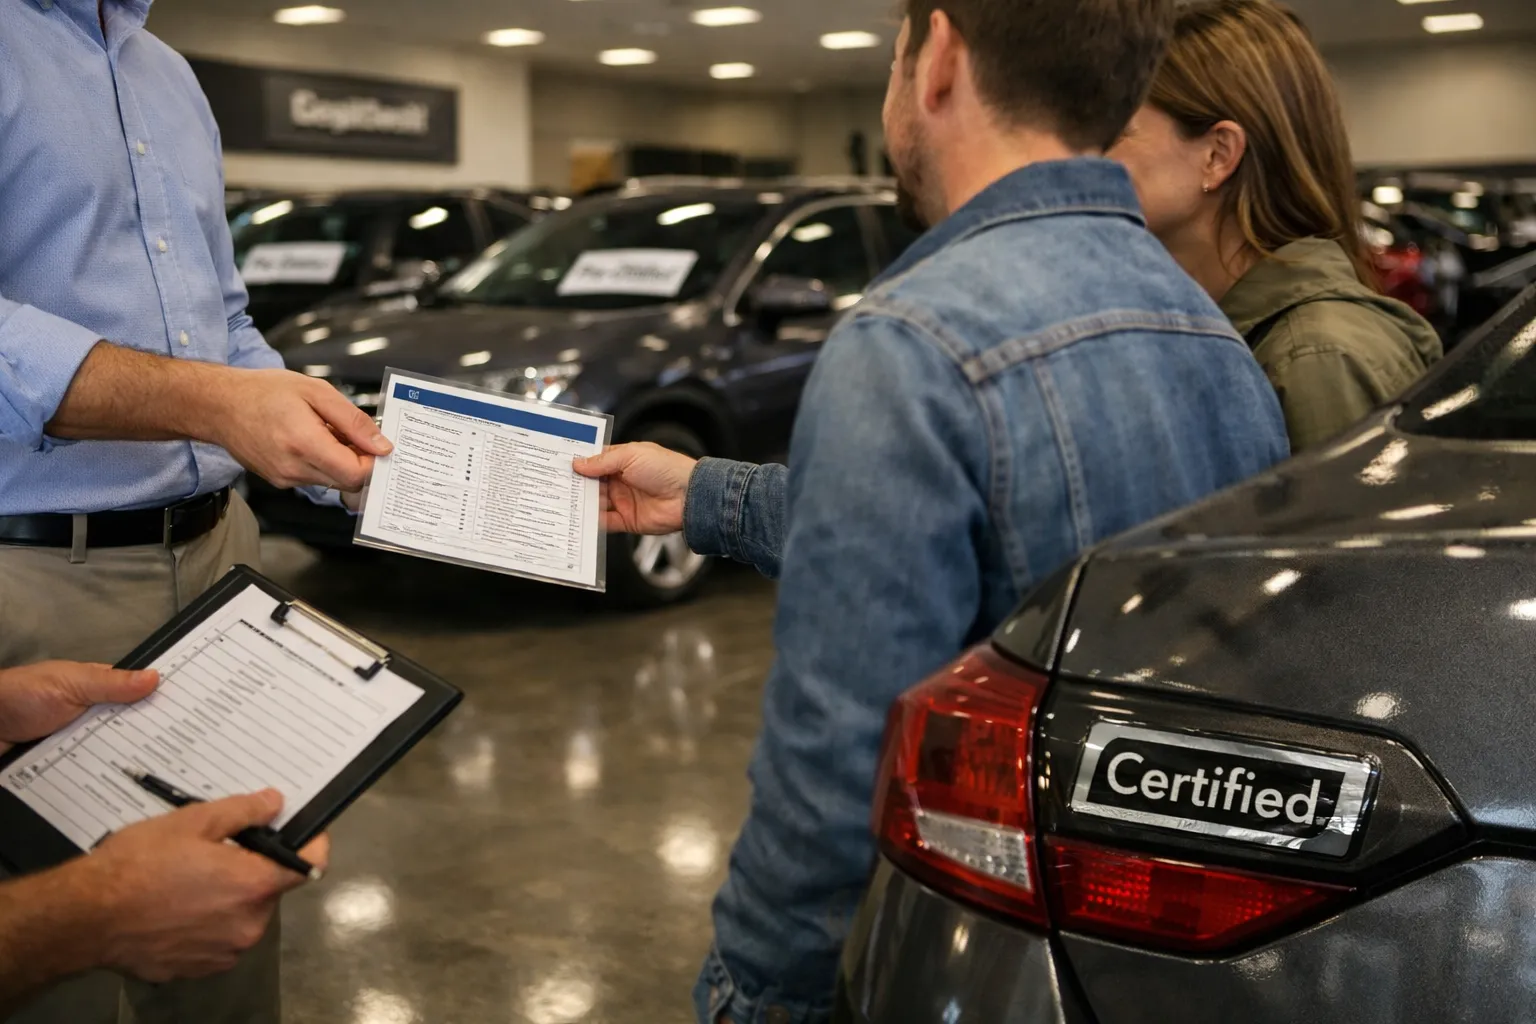
Certified pre-owned (CPO) vehicles regained noticeable pricing power across U.S. retail markets in 2025–2026. After several years in which broad used-car volatility and rising OEM inventory pushed discounts and blurred the line between certified and non-certified examples, the CPO premium has re-emerged. This analysis explains why, examines the market dynamics and provides evidence-based guidance for buyers deciding whether to pay for certification.
What "CPO premium" means now
Throughout this piece, "CPO premium" denotes the incremental price buyers pay for a certified pre-owned vehicle compared with a comparable non-certified used vehicle of the same model year, mileage and condition at retail. The premium reflects multiple elements: extended warranty coverage, standardized inspections, dealer-backed assurances (like vehicle history checks), and nominal marketing value to risk-averse buyers.
Three structural drivers behind the premium's return
1. Re-normalized wholesale markets and tightened late‑model supply
Wholesale used-vehicle prices stabilized after the extreme volatility of the pandemic and early 2020s. That stabilization—coupled with a slower-than-expected replenishment of newer used-car turnover—created a scarcity of clean, late-model examples that qualify for CPO programs. Dealers and OEMs who control CPO pipelines (off-lease returns, carefully sourced trade-ins, dealer-certified acquisitions) found that well-preserved, low-mileage examples became more valuable relative to higher-mileage, non-certified inventory.
2. Warranty economics and risk transfer regained relevance
As consumers weigh total cost of ownership more carefully—fuel/energy costs, repair incidence, and the prospect of major component failures—an OEM-backed warranty regained purchase utility. For many buyers, paying a premium to transfer the risk of expensive repairs to the OEM or dealer is cheaper than replacing parts out of pocket or buying stand-alone third-party coverage. OEMs in turn tightened CPO inspection protocols or extended limited warranties on some programs, increasing the perceived value of certification.
3. Dealer channel strategies shifted toward quality over quantity
Facing margin pressure in retail operations, many dealer groups prioritized turn-ready, higher-margin inventory. That led to a conscious shift: fewer price-driven volume trades and more investment in certifying vehicles that could carry a premium. CPO cars also aid finance and insurance (F&I) revenue streams, making certification a viable margin optimization tool for dealers with constrained inventories.
Evidence from market signals
Multiple industry indicators point to a stronger CPO valuation environment. Retail listings show a higher proportion of certified badges on later-model, lower-mileage vehicles than in the mid-2020s trough. Dealership advertising has emphasized extended certified warranties and inspection checklists more than price discounts, signaling confidence in value retention. Separately, auction houses and wholesalers report a higher conversion rate of off-lease returns into CPO-eligible units, reflecting both tightened qualification criteria and strategic inventory allocation.
How CPO stacks up against close alternatives
Buyers commonly face three choices when shopping late-model used cars: certified pre-owned, non-certified dealer-retail units with dealer reconditioning, and private-party purchases (often supplemented with third-party warranties). The tradeoffs are:
- CPO: Higher up-front cost, OEM warranty coverage, standardized inspection and certification, transferability in many programs, stronger appeal for buyers seeking low ownership risk.
- Dealer-retail non-CPO: Lower price than CPO, variable reconditioning and warrantied coverage (often limited), negotiable F&I add-ons. Value depends heavily on the dealer’s reconditioning standards and warranty product.
- Private-party + third-party warranty: Lowest price, highest buyer effort and risk. Third-party warranties can be cost-effective for some buyers but vary widely in coverage and claims handling quality.
When the premium makes sense
For buyers who plan to keep a vehicle more than three years, who want near-new ownership certainty, or who lack access to trusted independent inspection and warranty options, the CPO premium can be worthwhile. CPO often delivers convenience—standardized inspection, clear warranty terms and dedicated dealer support for claims—that many shoppers value beyond pure dollars.
When to skip certification
If the price gap is large, the buyer has mechanical expertise or access to a trusted independent inspector, or the vehicle falls outside strong warranty concerns (e.g., simple, low-cost models), non-certified options can be a better value. Similarly, buyers focused on short-term ownership horizons or total cost minimization may prefer non-CPO examples paired with limited third-party coverage.
How to quantify the break-even for your situation
Rather than rely on headline "average premiums," buyers should perform a simple break-even analysis:
- Compare retail prices for CPO and closely matched non-CPO units (same trim, features, mileage).
- Estimate the out-of-pocket repair risk over your intended ownership horizon (use vehicle reliability ratings and common failure risks for that model).
- Factor in the value of peace-of-mind elements: roadside assistance, trip-interruption cover, and transferability if resale is planned.
- Include finance rate differences—certified vehicles occasionally qualify for lower captive finance rates that partially offset the premium.
If the expected avoided repair expenses plus financing and resale advantages exceed the price gap, certification is justifiable.
Buyer checklist when evaluating a CPO purchase
- Obtain the full CPO terms in writing: warranty duration, mileage limits, covered components, claims process and transferability.
- Compare identical equipment levels and odometer readings to isolate the premium for certification only.
- Request inspection documentation and the dealer’s reconditioning invoice to understand what was repaired or replaced.
- Check for any exclusions (e.g., wear-and-tear items, wheel alignment, or battery coverage) and ask for clarifications.
- Shop captive finance offers; lower APRs can materially change the economics.
- Negotiate the overall deal—not just the CPO fee—since dealers often have flexibility on price or dealer-installed options.
Risks and headwinds for the CPO premium going forward
Several factors could ease or reverse the premium:
- Off‑lease waves: If major lease cohorts begin returning in large numbers, CPO-eligible supply could swell and compress the premium.
- OEM cost pressures: To protect retail volumes, some manufacturers may relax certification thresholds or increase CPO marketing, diluting scarcity value.
- Shifts in buyer preferences: If a new generation of buyers prioritizes lower monthly payments or subscription ownership models, willingness to pay a CPO premium may decline.
Practical takeaways for car buyers in late 2026
- Treat CPO as an insurance and convenience product with a measurable price. It is rarely a pure bargain; its value depends on your ownership horizon and risk tolerance.
- Do the math: compare total cost of ownership, not just sticker price. Factor in likely repairs, possible finance-rate benefits and resale expectations.
- Investigate the specific CPO program. Programs differ materially by OEM and even by region; read the contract before assuming one CPO is equivalent to another.
- Negotiate. CPO cars command premiums but dealers still price for movement; the final out-the-door figure is negotiable.
In 2025–2026, CPO cars reclaimed a place in the market as a durable product offering that bundles risk transfer and quality assurance. For buyers who value that combination—and who evaluate the math for their particular circumstances—the premium is often justified. For price‑sensitive buyers with alternatives for inspection and warranty, non-certified options remain compelling. Understanding the structural drivers and running a simple break-even exercise will tell you which side of that tradeoff you should choose.