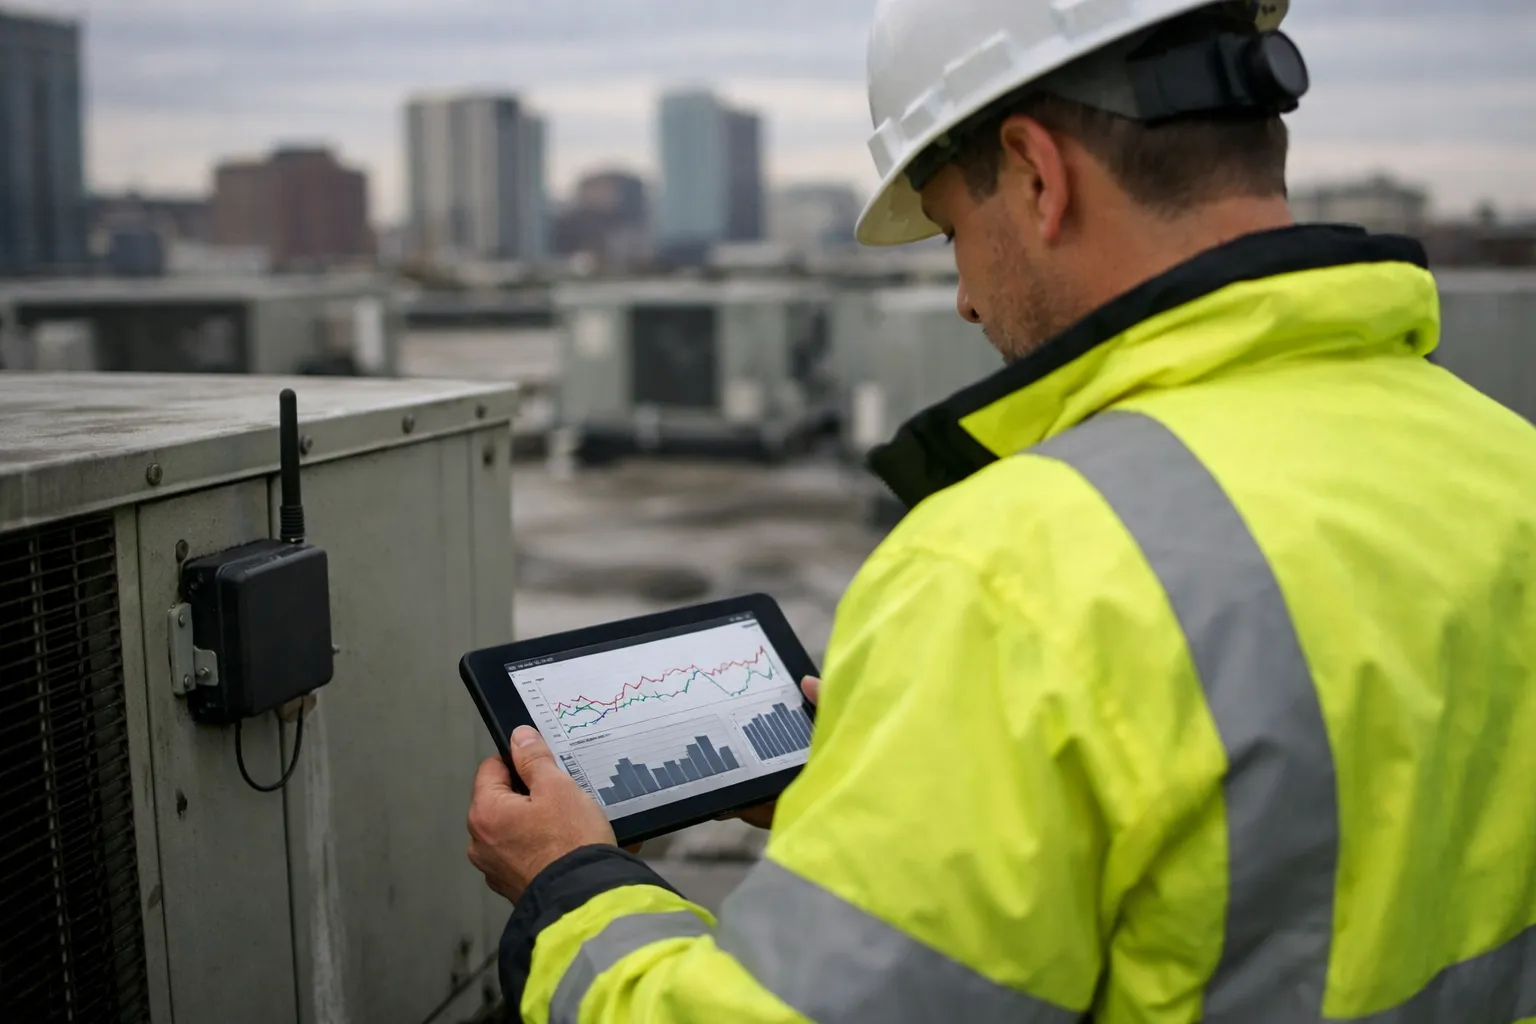
Over the past month a growing number of commercial property underwriters have begun tying premium discounts and eligibility for preferred coverage tiers to continuous refrigerant monitoring and remote-control capabilities for HVAC systems. The change is already reshaping retrofit priorities for building owners, creating new revenue streams for contractors, and prompting manufacturers to certify sensor and gateway packages to meet insurer specifications.
What changed — and why it matters
Underwriting teams at multiple large commercial insurers say they are recalibrating HVAC-related risk exposure after seeing an uptick in costly losses tied to refrigerant leaks, compressor failures and resultant water damage and business interruption. As a result, insurers are offering reduced premiums or requiring continuous telemetry from refrigeration and HVAC equipment as a condition of favorable terms for medium-to-large commercial properties.
That telemetry typically includes:
- Continuous refrigerant-pressure and temperature monitoring on critical circuits
- Automated alarm forwarding to building operators and brokers (24/7)
- Remote shutdown capability for units that leak or exhibit rapidly degrading pressures
- Encrypted, authenticated data transport and tamper detection on gateways
Insurers say these measures reduce the frequency and scale of losses by shortening detection-to-response time and enabling remote containment. For building owners, that can mean both lower premiums and fewer catastrophic incidents that trigger major property or business-interruption claims.
How the underwriting requirements are described
Although the exact language varies by carrier, brokers and risk managers reporting the change to HVAC System Guide describe three common models:
- Mandatory telemetry for buildings above a square-footage threshold to qualify for standard commercial property coverage.
- Voluntary sensor-and-monitoring deployments that qualify a building for defined premium credits (often 5–15% on the HVAC-related portion of the policy).
- Hybrid provisions requiring both monitoring and documented maintenance contracts with certified HVAC service providers to qualify for the highest discounts.
Underwriting partners emphasize that insurers are not prescribing a single sensor brand or protocol, but are specifying minimum performance and security requirements: continuous (not periodic) monitoring, tamper-evident gateways, time-synced logs, and the ability to generate actionable alarms for both internal facilities teams and designated third-party responders.
Impact on contractors and equipment vendors
The underwriting shift is accelerating retrofit demand. Contractors reporting new business describe requests for integrated solutions: on-unit refrigerant sensors, smart pressure transducers, cloud gateways with TLS encryption, and dashboard subscriptions that meet broker checklists.
“We’ve seen inquiries jump within weeks,” said a mid‑Atlantic service contractor. “Building owners want documented systems that an insurer will accept — not prototype sensor installs.”
In response, OEMs and independent sensor vendors are fast-tracking warranties and insurer-ready certification packages. These packages bundle hardware, encrypted connectivity, 24/7 alarm forwarding, and documented service-level agreements (SLAs) for alarm response — all items underwriting teams are looking for when evaluating discount eligibility.
What building owners should do now
Property managers and owners should take an audit-first approach:
- Inventory HVAC equipment by risk category (rooftop units, chillers, split systems, refrigeration circuits) and square footage served.
- Request underwriting checklists from your broker to identify specific telemetry and SLA requirements tied to your policy.
- Prioritize deployments on high-risk assets: large chillers, packaged rooftop units on critical-tenant spaces, and refrigeration systems in retail or food-service facilities.
- Work with contractors to get written confirmation that a proposed monitoring package will meet insurer requirements and provide the necessary logs for audits.
Because insurers also value documented maintenance, pairing monitoring deployments with scheduled preventive maintenance contracts increases the odds of securing preferred terms.
Opportunities and risks for the HVAC trades
The underwriting shift represents a revenue opportunity: sensor sales, gateway installations, subscription monitoring, and faster emergency-response contracts. However, it raises technical and organizational challenges. Contractors must now demonstrate secure telemetry implementations — including encryption, unique device IDs, and authenticated firmware updates — and support handoffs to brokers and insurance auditors.
Smaller contractors unfamiliar with cloud gateways or encrypted telemetry may need partnerships with specialized integrators or certified vendors to remain competitive. Trade groups are already discussing training modules and certification ladders to help the workforce meet insurer expectations.
What’s next
Expect insurers to refine requirements over the next 6–12 months, adding specific clauses around data retention, alarm escalation windows, and third-party verification. At the same time manufacturers will publish insurer-ready packages and certified integrations with common building-management systems.
For building owners the calculus is straightforward: investment in continuous refrigerant monitoring and documented remote-control capabilities can lower insurance costs and reduce risk of disruptive losses. For contractors, the change is both a call to upskill and a new line of business — one that blends traditional mechanical service with connectivity and data management.
HVAC professionals should coordinate now with brokers and vendors to define acceptable technical baselines, document deployments for auditors, and develop maintenance and alarm-response SLAs that underwriters will accept. Those who move quickly will capture the first wave of retrofit demand and build recurring revenue through monitoring subscriptions tied directly to insurance incentives.